Mostly yes — check P/TBV.
Thesis
Bull case
Citi holds 11%+ RoTCE through the investment ramp, 2027 EPS of $13.09 gets revised up further (revisions already 6-up/2-down), the fee-heavy Services/Wealth mix (31.2% Services RoTCE, record $38B net-new assets) earns a structurally higher multiple, Banamex deconsolidation proves CET1-positive and clears the path to a 2027 IPO, and ~$12–13B/year of buybacks at 1.2x book compounds TBVPS. Credible progress toward 13% RoTCE supports 1.4–1.5x TBV, i.e., $140–150+ within 12 months.
Bear case
The raised FY guide still implies a soft Q4 as investment is pulled forward; the ~$9B Banamex CTA charge creates a headline-loss quarter around held-for-sale classification; consent-order remediation keeps the efficiency ratio stuck; cards credit normalizes upward; and the forward P/E already sits 5–14% above Citi's own 5-year average. If RoTCE dips below 11% while spending rises, the market re-rates Citi back toward ~1.0x TBV — roughly $100, or ~18% downside — with the idiosyncratic 1-month lag vs XLF an early sign of exactly that rotation.
What would change our mind
- For a bearish/avoid stance: Q4 2026 RoTCE prints at or above ~11% with expenses contained, which would falsify the implied-soft-Q4 read and support the 2027–28 trajectory
- For a bullish stance: two consecutive quarters of RoTCE below 11%, or FY27 consensus EPS ($13.09) revised down >5%, or buybacks cut materially below ~$2.5B/quarter — each would signal the 1.2x TBV multiple is unsupported
- Banamex deconsolidation slipping beyond 2027 or the IPO being shelved would push out the monetization catalyst and extend the CTA overhang
Since publication vs SPY · closed horizons are frozen
No price data after the entry date yet.
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
At ~1.2x TBV and ~9.3–10.1x forward earnings, the price assumes Citi sustains RoTCE above 11% and makes visible progress toward the 11–13% 2027–28 target, that buybacks near the current ~$3B/quarter pace continue, and that Banamex deconsolidation and its ~$9B CTA charge are absorbed without derailing reported returns. The market is no longer pricing a discount-to-book re-rating — that trade has largely been captured in the +25.7% one-year move.
Why the market may be wrong
In both directions. Bearish miss: the market may be underpricing the implied soft Q4 — YTD RoTCE of 12.6% against a merely '>11%' FY guide means management expects Q4 meaningfully below the run-rate as investment is pulled forward, and the Banamex CTA timing could land as an ugly headline quarter. Bullish miss: the market may be underpricing the quality shift — Services (31.2% RoTCE) and Wealth ($38B record net-new assets) are fee-heavy, capital-light businesses, and 2027 EPS revisions are skewed 6-up/2-down; if mix shift is durable, 13%+ RoTCE would justify 1.4–1.5x TBV. Neither side has a decisive fact yet.
The one thing to watch
The variable to watch has flipped: for a decade the Citi question was 'how big is the discount to tangible book,' but at 1.2x TBV the discount trade is finished and the live question is whether RoTCE holds the 11% floor while spending ramps — and the single most under-discussed fact is that Citi's own guidance arithmetic (12.6% YTD vs. '>11%' FY) implies Q4 RoTCE is guided down toward ~8–9%, meaning the next print will look like deterioration even if the plan is on track.
Key evidence (8)
- Q3 2026 (reported Oct 13, 2026): revenue $23.8B (+8% y/y, best Q3 in a decade), diluted EPS $2.85 vs $1.86, RoTCE 11.5% (+350bp y/y; YTD 12.6%), efficiency ratio ~59%, CET1 12.8% [T1 SEC 8-K; Citi release]
- FY2026 RoTCE guidance raised to above 11% (from top of 10–11%); 11–13% target reiterated for 2027–28; 14–15% ambition for 2029–31 [Citi Q3'26 transcript, Reuters 2026-10-13 [T2]]
- TBVPS $101.59 as of 9/30/26, +6% y/y; price $122.64 implies ~1.21x tangible book [T1/Citi Q3'26 materials; market data 2026-11-02]
- Consensus (as of 2026-11-01, T4 aggregators): FY26 EPS $11.38, FY27 EPS $13.09 (+14.5%); forward P/E ~9.3–10.1x vs ~8.9x 5-year average
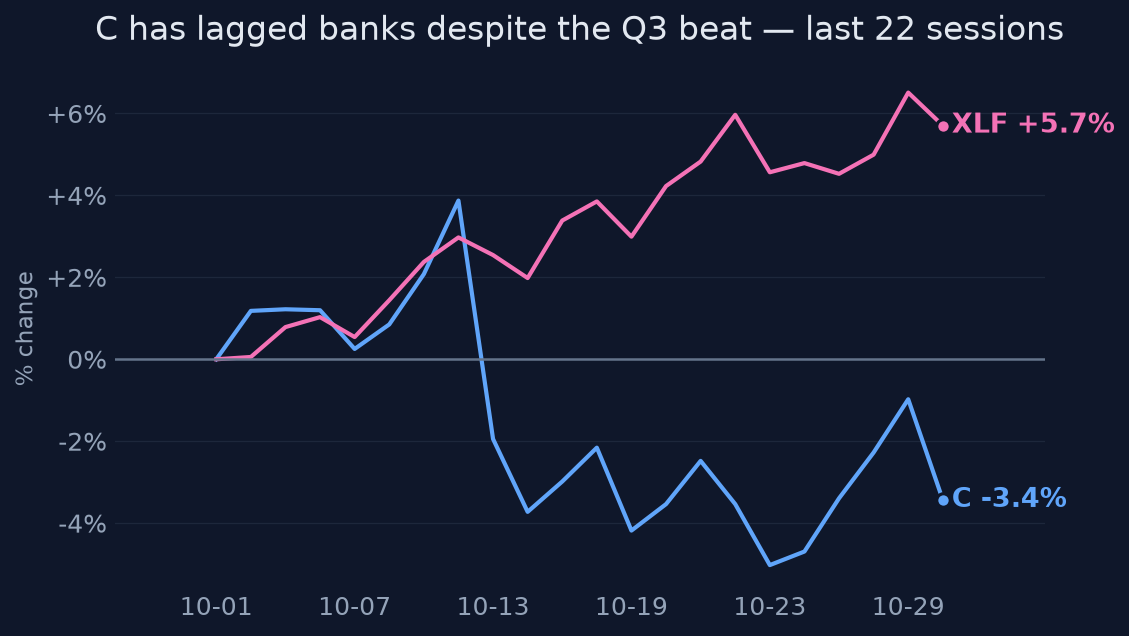
- Price action: +25.7% 1y but -8.2% 3m and -3.4% 1m; lagged XLF by ~9pts over the past month (idiosyncratic weakness); ~16% below 52w high, below 20d/50d SMAs, RSI ~33 [market data 2026-11-02]
- Banamex: 49% divested (51% retained); deconsolidation expected 2027 with ~$9B accumulated FX/CTA loss hitting reported earnings at held-for-sale classification; IPO timing uncommitted [Q3'26 materials]
- Capital return: >$4B returned in Q3 (~$3B buybacks); ~$13.3B repurchased through Q3 [Reuters 2026-10-13 [T2]]
- U.S. Cards net credit losses ~4.0%, at low end of 4.0–4.5% guidance — credit is not the current problem [Citi Q3'26 presentation]
Catalysts and risks
Catalysts
- Q4 2026 earnings (mid-January 2027) — first test of the raised >11% FY26 RoTCE guide and the implied soft-Q4 arithmetic
- Banamex held-for-sale classification timing — triggers the ~$9B CTA charge and clarifies the 2027 deconsolidation/IPO path
- Quarterly RoTCE prints vs the 11% floor and commentary on the 11–13% 2027–28 target
- Buyback pace disclosure (~$3B/quarter run-rate) and any CET1-guided change to capital return
- Any consent-order remediation milestones or new regulatory actions
- 2027 EPS estimate revisions (currently skewing positive)
Risks
- Banamex CTA charge (~$9B) produces a headline-loss quarter that pressures reported EPS/RoTCE and invites multiple compression even if CET1 impact is positive
- Pulled-forward investment spending pushes the efficiency ratio back up and delays the 11–13% target
- Unresolved consent orders keep remediation costs elevated and cap capital-return flexibility
- Valuation no longer cheap vs own history (forward P/E above 5y average; 1.2x TBV vs years below 1.0x) leaves no valuation cushion
- Idiosyncratic recent weakness (-9pts vs XLF over 1m) may signal holders rotating out ahead of the Q4 print
- Cards credit (NCLs 4.0%) normalizing above guidance in a weaker macro tape
What to watch
- Price-to-tangible-book around the ~1.2x level: a break back toward 1.0–1.1x on no fundamental news is the re-entry zone; expansion above 1.3x requires RoTCE evidence
- Quarterly RoTCE vs the 11% floor — specifically the Q4'26 print in January given the 12.6% YTD vs '>11%' FY guide arithmetic
- FY27 EPS revision direction (currently 6 up / 2 down over 30 days)
- Banamex: held-for-sale classification date, CTA charge quarter, and any firm IPO timeline
- Buyback run-rate per quarter and CET1 trajectory (12.8% now, 120bp above requirement)
- Relative performance vs XLF/JPM — continued idiosyncratic lag would confirm the market is pricing execution risk, not sector risk
Market snapshot when the call was made 2026-10-30
Price
| Return 1w | +1.7% |
| Return 1m | -3.4% |
| Return 3m | -8.2% |
| Return 6m | -3.3% |
| Return 1y | +25.7% |
| From 52-week high | -15.8% |
| Realized vol, 20d | 29% |
| SPY 3m / 1y | -0.3% / +9.9% |
| QQQ 3m / 1y | -1.4% / +8.6% |
Technicals
C technicals as of 2026-10-30: last close $122.64; 20d SMA 124.79 (bearish); 50d SMA 130.01; 12d EMA 123.76; 26d EMA 125.87; RSI 14 33.3 (balanced); 20d vol 28.6%; volume x1.5 vs 20d avg
Sources (11 · T1 = primary filings)
- T4https://www.citigroup.com/rcs/citigpa/storage/public/Earnings/Q32026/3q26-citigroup-earnings-transcript.pdf
- T2https://www.reuters.com/business/finance/citi-profit-jumps-40-with-higher-investment-banking-services-wealth-r…
- T4https://www.citigroup.com/rcs/citigpa/storage/public/Earnings/Q32026/2026psqtr3rslt.pdf
- T4https://www.citigroup.com/global/investors/quarterly-earnings/faqs
- T4https://www.citigroup.com/rcs/citigpa/storage/public/Earnings/Q32026/2026fsqtr3rslt.pdf
- T1https://www.sec.gov/Archives/edgar/data/831001/000110465926115323/c-ex99d1.htm
- T4https://au.investing.com/news/stock-market-news/earnings-call-transcript-citigroup-beats-q3-2026-estimates-as-…
- T4https://www.citigroup.com/global/investors/sec-filings
- T4https://www.citigroup.com/rcs/citigpa/storage/public/Earnings/Q32026/3q26-earnings-8-k-10-13-26.pdf
- T4https://www.openbookanalytics.com/news/insights/citigroup-c-stock-analysis-share-price-fundamentals-earnings-v…
- T4https://www.theglobeandmail.com/investing/markets/stocks/MS/pressreleases/6851343/jpm-q3-earnings-lag-on-lower…
Earlier and later calls on C
- Oct 12, 2026Beat alone won't re-rate it.Neutral
Want a fresh look at C, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Nov 2, 2026. Not personalised advice. Figures use end-of-day closes.