Oversold, but cash-flow risk is real.
Thesis
Bull case
Ads growing 26% with AI demonstrably improving ad performance; Q4 guide above consensus; FY27 EPS stable at $34.13; at 18x FY27 the stock is priced like a broken business while growing revenue and ads 26% y/y. The legal overhang is now largely quantified ($18B/decade). If January's 2027 capex guide is anywhere near $200B rather than $250B, the negative-FCF thesis collapses and the multiple re-rates toward 22x+ (~$750). RSI 17.6 and a 1.5-sigma monthly drop suggest capitulation-adjacent positioning.
Bear case
FCF is negative now, Q4 consensus is -$15B, and management gave no 2027 capex number while disclosing $825B of commitments — analysts model $200-250B for 2027. Buybacks are gone, the balance sheet is net-debt neutral, and the Class C structure telegraphs dilutive equity issuance as early as January 2027. Depreciation from a $250B capex year would hit FY27-28 EPS hard, meaning the 'stable' FY27 consensus may simply not have caught up — the FY26 revision pattern (-8.3% in 3 months) may repeat a year forward. Reality Labs losses are only expected to narrow to ~$15B by 2027, implying an even larger drag today, and EU DSA actions target engagement mechanics directly.
What would change our mind
- 2027 capex guidance exceeds ~$250B or management signals multi-year negative FCF with no monetization timeline — the bear case is confirmed, not priced
- FY27 EPS consensus breaks below ~$31 (a >8% cut mirroring FY26's pattern), proving depreciation is not in numbers
- A Class C capital raise above ~$20B announced within 6 months
- Ad revenue growth decelerates below ~15% y/y in Q4, removing the core engine funding the spend
Since publication vs SPY · closed horizons are frozen
No price data after the entry date yet.
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
At $615 (~21x FY26, ~18x FY27 EPS), the market appears to assume: (1) 2027 capex of $200B+ with multi-year negative FCF, (2) continued suspension of buybacks and potential dilutive Class C issuance, (3) limited near-term AI revenue payoff beyond ad performance, and (4) that FY27 EPS estimates face downward revision as depreciation from $140B+ annual capex flows through.
Why the market may be wrong
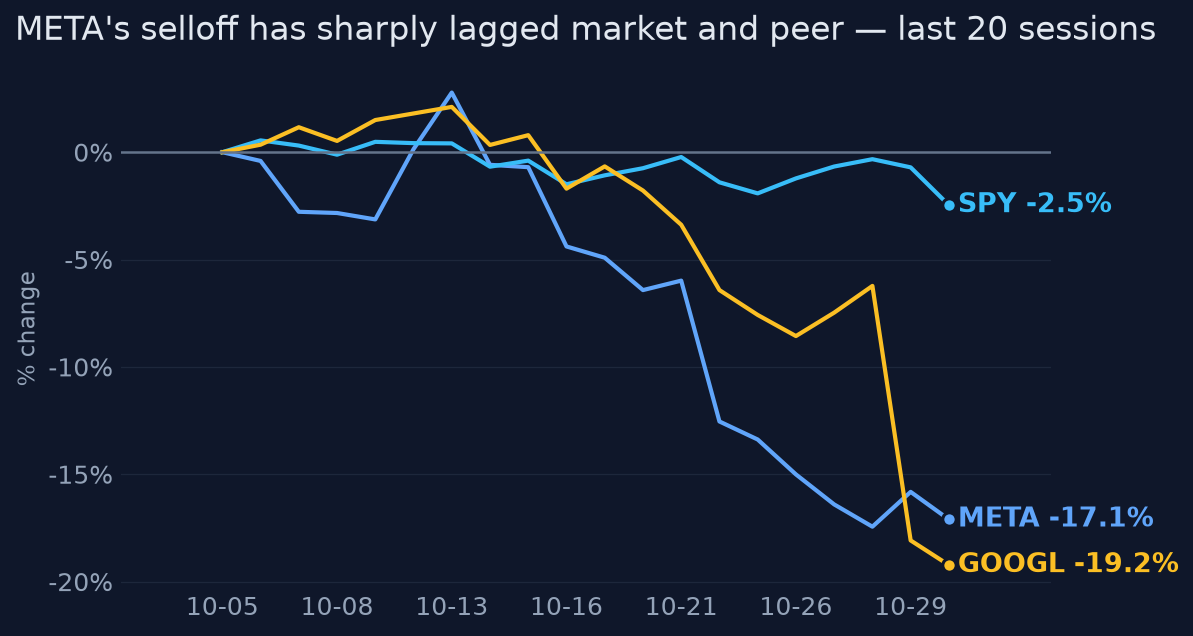
Two internal contradictions suggest over-pricing of the bear case: FY27 EPS estimates are stable (+0.2% over 3 months) even as analysts model 2027 capex doubling to ~$250B — either the depreciation hit isn't in numbers (bearish surprise) or consensus doesn't believe the high-end capex scenarios (in which case the FCF fear is overstated). Also, the market punishes negative-FCF spenders selectively (GOOGL -13% on earnings) while rewarding cash-generative ones (MSFT +5%); META initially popped 2.5-3.8% post-Q3, meaning the subsequent 15% slide is about commitment disclosures and trajectory fear more than deteriorating fundamentals.
The one thing to watch
The variable to watch is not revenue or EPS — it's the FY27 capex guide at the January 2027 earnings call versus the ~$200B low-end analyst expectation: the entire 15% selloff is a bet that Meta guides 2027 capex toward $250B, so any guide at or below ~$210B forces bears to re-underwrite the whole negative-FCF thesis against an 18x multiple.
Key evidence (10)
- Q3 2026 (Oct 21): revenue $64.6B (+26% y/y) beat ~$63.4B consensus; Q4 guide $73-76B above ~$73.7B consensus [T1/T2]
- Q3 FCF negative $2.1B vs +$10.6B a year earlier; Q4 FCF consensus ~negative $15B [T2/FactSet]
- FY26 capex raised to $135-145B; ~$825B disclosed future spending commitments, up from ~$700B [T2]
- Buybacks fully suspended in 2026 vs $26.25B repurchased in 9M 2025; dividend maintained (~$5.4B/yr) [T1]
- Balance sheet 9/30/26: $82.4B cash+securities vs ~$83.7B debt — effectively net-debt neutral; $24.9B new debt issued 2026 [T1]
- Non-voting Class C share class announced Oct 2026, 1-for-1 distribution, effective Jan 2027 — an equity-financing lever preserving Zuckerberg control [T2 Reuters]
- FY26 EPS revised down 8.3% to $29.18 over 3 months; FY27 stable at $34.13 [MarketWatch consensus, Oct 30 2026]
- Price: -15.3% 1M, -18.2% 1Y, 21% below 52w high, RSI 17.6; 83% idiosyncratic variance vs SPY [quant data]
- $9.9B legal charge tied to settlement with 52 state AGs; Reuters reports up to $18B over a decade plus teen-use restrictions [T2, Aug 27 2026]
- Sector de-rating is selective: GOOGL -13% on earnings, MSFT +5% — market discriminates on FCF credibility [T2]
Catalysts and risks
Catalysts
- Q4 2026 earnings (late Jan 2027): first formal 2027 capex guidance — the single biggest thesis variable
- Class C share distribution effective January 2027 — watch for any announced issuance/sale
- Q4 FCF print vs the ~negative $15B consensus
- EU DSA preliminary findings on under-13 access and design-change mandates
- Peer Q4 capex prints (GOOGL/MSFT/AMZN, Jan-Feb 2027) setting the sector's FCF-credibility tone
Risks
- 2027 capex guided at/above $250B, extending negative FCF into 2028
- Class C equity issuance announced, diluting holders while FCF is negative
- FY27 EPS revisions turn negative as depreciation from 2026-27 capex is modeled in
- Further youth-safety/private litigation beyond the AG settlement
- EU-mandated design changes (autoplay, recommendation defaults) reduce engagement and ad pricing
What to watch
- 2027 capex guidance at January earnings vs the $200B low-end analyst expectation
- Q4 FCF vs -$15B consensus; any commentary on FCF trough timing
- Class C share usage: compensation/acquisitions vs outright cash raise
- FY27 EPS revision trend — flat or rising supports the thesis, accelerating cuts kill it
- Buyback resumption language; dividend is safe but buybacks are the FCF tell
Market snapshot when the call was made 2026-10-30
Price
| Return 1w | -4.3% |
| Return 1m | -15.3% |
| Return 3m | +4.2% |
| Return 6m | +1.0% |
| Return 1y | -18.2% |
| From 52-week high | -20.9% |
| Realized vol, 20d | 38% |
| SPY 3m / 1y | -0.3% / +9.9% |
| QQQ 3m / 1y | -1.4% / +8.6% |
Technicals
META technicals as of 2026-10-30: last close $614.99; 20d SMA 691.11 (bullish); 50d SMA 669.98; 12d EMA 653.19; 26d EMA 673.89; RSI 14 17.6 (oversold); 20d vol 36.1%; volume x1.1 vs 20d avg
Verifier notes REVISE · opinion revised once
Unsupported claims
- Bull case asserts META is 'delivering hyperscaler-best top-line growth.' The evidence verifies META's own +26% growth but contains no peer revenue-growth figures for GOOGL, MSFT, or AMZN — the bundle only documents peer capex levels, FCF, and stock reactions. The comparative superlative is unverifiable from this bundle and should not be stated as fact.
Corrections applied
- In the bull case, replace 'while delivering hyperscaler-best top-line growth' with the evidence-supported 'while growing revenue/ads 26% y/y' (or add peer growth data to the evidence bundle to substantiate the comparison).
- Minor (non-blocking): the bear case says 'Reality Labs still loses ~$15B/yr,' but the evidence states losses are expected to narrow TO ~$15B by 2027, implying current losses are larger. Consider 'Reality Labs losses are only expected to narrow to ~$15B by 2027' for precision.
Sources (29 · T1 = primary filings)
- T2https://www.reuters.com/business/meta-issue-new-class-shares-it-tightens-ai-spending-forecast-2026-10-21/
- T4https://finance.yahoo.com/quote/META.MX/earnings/META.MX-Q3-2026-earnings_call-718643.html
- T2https://www.bloomberg.com/news/live-blog/2026-10-21/meta-third-quarter-earnings-live-updates
- T4https://www.theglobeandmail.com/investing/markets/stocks/META/pressreleases/8324475/why-meta-meta-shares-are-g…
- T4https://investinglive.com/stocks/meta-q3-beats-on-revenue-and-eps-as-9-9b-legal-charge-lifts-full-year-expense…
- T4https://fortune.com/2026/10/21/meta-q3-earnings-mark-zuckerberg-capex-muse/
- T3https://cnbc.com/2026/10/21/meta-earnings-q3-2026-live-updates.html
- T4https://finance.yahoo.com/video/wells-fargo-cuts-meta-price-002001458.html
- T2https://www.reuters.com/business/alphabets-google-cloud-unit-beats-quarterly-revenue-estimates-steady-ai-deman…
- T1https://investor.atmeta.com/investor-news/press-release-details/2026/Meta-Reports-Third-Quarter-2026-Results/d…
- T3https://cnbc.com/2026/10/29/microsoft-google-ai-capex-estimates.html
- T3https://www.cnbc.com/2026/10/22/meta-stock-q3-earnings-free-cash-flow.html
- T3https://www.cnbc.com/2026/10/29/alphabet-google-microsoft-msft-shares-today-earnings.html
- T3https://www.cnbc.com/2026/10/30/tech-giants-alphabet-meta-microsoft-amazon-ai-buildouts.html?taid=6ae47bbc25ed…
- T3https://www.cnbc.com/2026/10/21/meta-earnings-q3-2026-live-updates.html
- T4https://uk.investing.com/news/stock-market-news/earnings-call-transcript-meta-beats-q3-2026-estimates-as-ai-pu…
- T2https://www.reuters.com/business/why-is-meta-creating-new-class-non-voting-shares-amid-its-ai-growth-2026-10-2…
- T4https://techcrunch.com/2026/10/21/meta-wants-to-pay-for-its-broad-ai-buildout-with-a-newly-created-class-of-st…
- T4https://finance.yahoo.com/markets/stocks/articles/meta-creates-non-voting-stock-190602135.html
- T4https://fortune.com/2026/10/21/zuckerberg-meta-california-wealth-tax-billions-class-c-stock/
- T4https://finance.yahoo.com/markets/stocks/articles/meta-creating-class-stock-shareholders-111552092.html
- T4https://finance.yahoo.com/markets/stocks/articles/meta-stocks-put-ai-financing-181858557.html
- T4https://www.law360.com/mlex/data-privacy-security/articles/2541024/meta-says-youth-related-legal-costs-drove-6…
- T4https://finance.yahoo.com/markets/stocks/articles/meta-meta-q3-2026-earnings-005815826.html?fr=sycsrp_catchall
- T4https://finance.yahoo.com/markets/stocks/articles/meta-platforms-q3-earnings-call-230315336.html
- T4https://www.stocktitan.net/articles/meta-q3-2026-earnings-results
- T2https://www.reuters.com/world/china/meta-settlement-opens-new-front-global-fight-over-social-media-harm-2026-0…
- T4https://www.stocktitan.net/news/META/meta-reports-third-quarter-2026-13ysmyjaxliq.html
- T4https://www.fortune.com/2026/10/21/meta-q3-earnings-mark-zuckerberg-capex-muse/
Earlier and later calls on META
- Oct 19, 2026Capex, not revenue, decides.No clear edgeview changed
- Oct 13, 2026No edge until Oct 21.No clear edgeview changed
- Oct 4, 2026No — the rally outran the evidence.Lean bearishview changed
- Aug 17, 2026Buy, but small and patient.Lean bullish
Want a fresh look at META, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Nov 1, 2026. Not personalised advice. Figures use end-of-day closes.