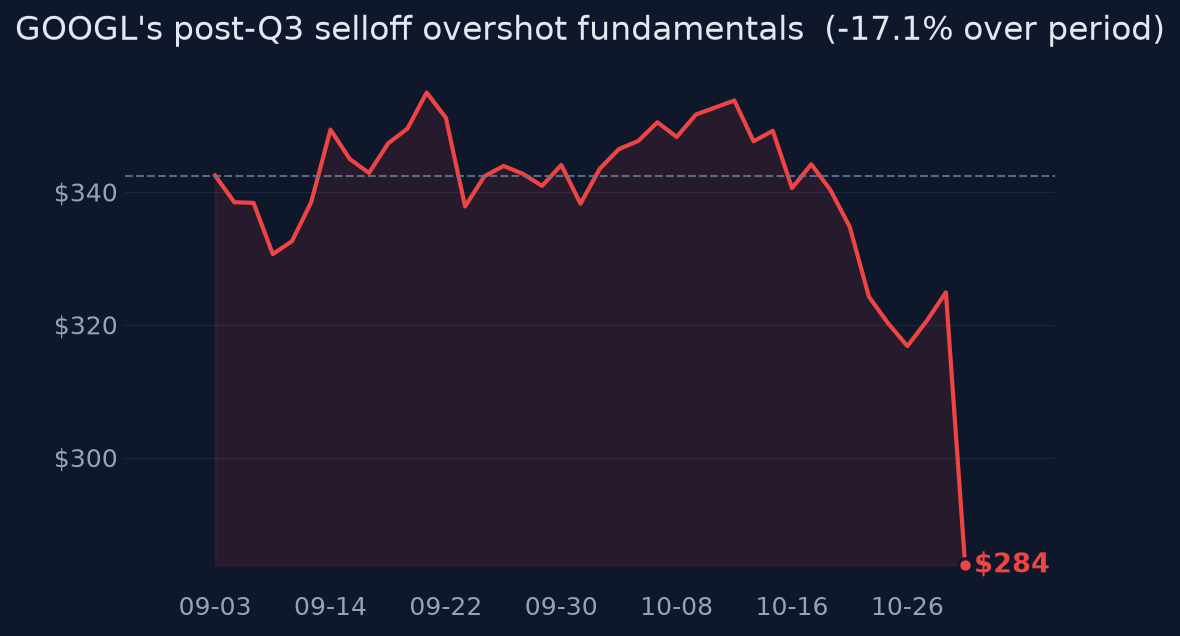
Yes — the selloff overshot.
Thesis
Bull case
Cloud doubling with a $560B+ contracted backlog proves AI demand; the FCF and GAAP-EPS misses are timing/accounting artifacts (accrued fine, unrealized investment marks); Search is growing with 5-year-high query growth, not losing share; regulatory worst cases are off the table. At ~18.5x FY27 EPS with ~$140B net cash and an oversold technical setup, any evidence of capex-to-revenue conversion on the Q4 call triggers a re-rating back toward the mid-20s multiple — 25-35% upside.
Bear case
This is the first negative-FCF quarter in 22 years, 2027 capex goes 'significantly higher' with no numeric FCF guide, and the market is systematically repricing every hyperscaler on funding risk (Meta's CDS at record highs). AI Mode monetizes below traditional Search — so even where Google wins AI queries, it wins them at lower economics. If consensus FY27 EPS of $15.36 is cut post-Q4-call, the 'cheap' 18.5x forward multiple is an illusion, and GOOGL becomes a capital-intensive utility growing into its spend.
What would change our mind
- FY27 consensus EPS cut below ~$13.50 within 4-6 weeks — confirms the 'cheap multiple' was an illusion
- Q4 call guides 2027 capex well above ~$230B without quantified FCF or backlog-conversion framing
- Cloud backlog declines sequentially or Cloud growth decelerates sharply — breaks the demand proof
- Search revenue growth drops to low single digits — would validate the AI-cannibalization bear case
- Buyback suspension or major new debt-equity funding signals structural, not transitional, FCF stress
Since publication vs SPY · closed horizons are frozen
No price data after the entry date yet.
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
The market has moved from rewarding AI spend to punishing it: GOOGL's forward P/E compressed from ~29x pre-earnings to ~21-23x in days, and the stock decoupled from MSFT/QQQ (idiosyncratic share 90%). Consensus (as of Oct 25) still models FY27 revenue +25% and EPS +29% — so the price is implying those estimates get cut materially once 2027 capex guidance lands.
Why the market may be wrong
The market is treating negative FCF as structural when ~$6.2B of it was one-time/regulatory cash timing (accrued Android fine + DMA charge), and treating the GAAP EPS drop as operational when it was unrealized equity-investment losses. If FY27 estimates hold while the stock sits 30% below its high, that is multiple compression, not deterioration — and a reversal candidate.
The one thing to watch
The variable to watch is not Search share (which the evidence shows is NOT eroding — query growth is at a 5-year high) but the capex-to-FCF conversion narrative on the Q4 call: the stock is now a referendum on whether $200B+/yr capex with 'significantly higher' 2027 guidance can be credibly tied to the $560.8B Cloud backlog. If management frames 2027 capex against contracted backlog rather than speculative demand, the multiple likely re-expands; if they don't, estimate cuts follow.
Key evidence (11)
- Q3 2026 (Oct 28): revenue $127.6B +25% YoY, small miss vs $128.2B [Reuters/CNBC]
- Google Cloud $30.7B, more than doubled YoY, beat estimates [Reuters, Oct 28 2026]
- Cloud backlog $560.8B (total $567.7B), up ~$47B sequentially — hard demand evidence [10-Q, T1]
- FCF -$9.1B = $42.3B op cash flow - $51.4B capex, but includes $5.2B accrued EU Android fine paid July 2026 + $1.0B DMA charge [10-Q-adjacent/CNBC]
- GAAP net income -25% driven by OI&E unrealized investment losses incl. SpaceX mark; operating income +30% to ~$40.6B [earnings coverage]
- Search revenue +12% to ~$63.3B; query growth fastest in 5 years; AI Mode monetizes below traditional Search (Schindler) [call]
- FY26 capex guide $195-205B maintained; 2027 'significantly higher', details on Q4 call [CFO commentary]
- Balance sheet: $265.1B cash+securities vs $125.1B debt (~$140B net cash) [10-Q]
- Regulatory worst cases avoided: DOJ search = conduct remedies, ad-tech = behavioral not divestiture [DOJ/court, T1]
- Forward P/E compressed ~29x → ~21-23x; ~18.5x FY27 consensus EPS of $15.36 [market data]
- Technical: RSI 15.6 oversold, 20d vol 100th percentile, -2.1σ 1-month move [quant analysis]
Catalysts and risks
Catalysts
- Q4 2026 earnings call (Jan/Feb 2027): numeric 2027 capex guidance and FCF framing — the single biggest swing factor
- Post-earnings analyst estimate revisions over the next 2-4 weeks (do FY27 EPS estimates hold near $15.36?)
- Buyback/dividend commentary — any increase in capital returns would signal FCF confidence
- DOJ search-remedies cross-appeals and ad-tech remedy implementation milestones
- Cloud backlog trajectory in Q4 print
Risks
- 2027 capex guided so high that FY27 EPS/FCF estimates are cut broadly
- Sector-wide AI-capex de-risking continues regardless of GOOGL-specific facts (META parallel weakness)
- AI Mode monetization gap persists, capping Search revenue quality
- Behavioral ad-tech remedies gradually erode take rates
- Further unrealized losses in the equity portfolio (SpaceX etc.) hitting GAAP EPS optically
What to watch
- FY27 EPS revision direction over the next month (hold at ~$15.36 = thesis intact)
- Q4 call: 2027 capex number and any FCF/buyback framing
- Sequential Cloud backlog change
- AI Mode monetization commentary — any move toward parity with traditional Search
- Hyperscaler sector CDS/funding stress as a sentiment tell
Market snapshot when the call was made 2026-10-29
Price
| Return 1w | -12.5% |
| Return 1m | -17.5% |
| Return 3m | -20.3% |
| Return 6m | -26.2% |
| Return 1y | +6.1% |
| From 52-week high | -29.5% |
| Realized vol, 20d | 51.9% |
| SPY 3m / 1y | +3.0% / +12.0% |
| QQQ 3m / 1y | +4.0% / +13.0% |
Technicals
GOOGL technicals as of 2026-10-29: last close $283.82; 20d SMA 337.09 (neutral); 50d SMA 340.29; 12d EMA 323.97; 26d EMA 333.38; RSI 14 15.6 (oversold); 20d vol 48.3%; volume x4.5 vs 20d avg
Verifier notes PASS
Weakly sourced
- 'GOOGL is the cheapest large-cap AI-infrastructure exposure' (why_this_matters) — the evidence contains no peer forward multiples for MSFT/META/AMZN, only GOOGL's own ~18.5x FY27 and ~21-23x forward P/E. The comparative claim rests on nothing in the bundle.
- Characterizing the full ~$6.2B ($5.2B Android fine + $1.0B DMA charge) as FCF 'cash timing': the evidence establishes the $5.2B accrued fine as a Q3 cash payment, but describes the $1.0B DMA item as an earnings/balance-sheet charge without confirming it was a cash outflow in the quarter. The cash-flow treatment of the DMA charge is an inference.
Corrections applied
- Soften 'cheapest large-cap AI-infrastructure exposure' to a claim the evidence supports, e.g. 'GOOGL now trades at ~18.5x FY27 consensus EPS after the multiple compression' — or add peer multiple evidence.
- Restate the FCF bridge as '~$5.2B of the negative FCF was the accrued EU Android fine payment (cash timing), plus a separate $1.0B DMA charge whose cash-flow timing is unconfirmed.'
Sources (32 · T1 = primary filings)
- T2https://www.reuters.com/business/alphabets-google-cloud-unit-beats-quarterly-revenue-estimates-steady-ai-deman…
- T3https://www.cnbc.com/2026/10/28/alphabet-googl-earnings-q3-2026.html
- T4https://abc.xyz/investor/events/event-details/2026/2026-Q3-Earnings-Call-2026-Ujou16CTw9/default.aspx
- T4https://static.poder360.com.br/uploads/2026/10/Alphabet-3Q26.pdf
- T3https://www.cnbc.com/2026/10/28/alphabet-googl-earnings-q3-2026.html?msockid=1f314c869c57630c101c54869d676206
- T4https://finance.yahoo.com/markets/stocks/articles/alphabet-inc-goog-q3-2026-050953011.html
- T4https://abc.xyz/investor/events/event-details/
- T4https://www.theglobeandmail.com/investing/markets/stocks/GOOGL-Q/pressreleases/8518440/alphabet-googl-q3-2026-…
- T2https://www.reuters.com/business/metas-credit-risk-indicator-jumps-record-high-after-results-2026-10-22/
- T2https://www.reuters.com/business/steep-bill-ai-buildout-punishes-meta-other-tech-favorites-2026-10-22/
- T2https://www.reuters.com/legal/transactional/ai-giants-funding-ambitions-test-wall-streets-appetite-risk-2026-1…
- T2https://www.reuters.com/technology/big-tech-earnings-test-ai-boom-amid-market-turmoil-2026-10-27/
- T2http://rmb.reuters.com/rmd/rss/item/tag:reuters.com,2026:newsml_KBN3W21RN?channel=frL012
- T2https://www.reuters.com/business/nasdaq-futures-drop-over-1-ai-worries-resurface-oil-climbs-2026-10-22/
- T2https://www.reuters.com/business/wall-st-week-ahead-earnings-flood-fed-meeting-pose-pivotal-tests-rickety-ai-2…
- T1https://www.sec.gov/Archives/edgar/data/1652044/000165204426000071/goog-20260630.htm
- T4https://www.benzinga.com/news/26/10/62679903/alphabet-q3-2026-earnings-call-transcript
- T4https://www.stocktitan.net/sec-filings/GOOGN/10-q-alphabet-inc-quarterly-earnings-report-9e9e43ebd2ea.html
- T1https://www.justice.gov/opa/pr/department-justice-again-wins-substantial-relief-against-google
- T4https://www.goodwinlaw.com/en/insights/publications/2026/10/insights-technology-antc-antitrust-competition-tec…
- T4https://news.futunn.com/en/notice/1002730315/quarterly-report
- T3https://www.cnbc.com/investingclub/2026/10/28/our-next-steps-for-alphabet-stock-after-earnings-disappoint-at-n…
- T4https://www.ibtimes.co.uk/alphabet-shares-fall-ai-spending-profit-miss-1828811
- T4https://eur-lex.europa.eu/eli/C/2026/4985/oj
- T4https://smart-goblin.com/GOOG/10-Q/2026-09-30-0001652044-26-000084/sections
- T4https://finance.yahoo.com/markets/stocks/articles/alphabet-googl-q3-2026-earnings-054403755.html
- T4https://searchengineland.com/google-earnings-call-q3-2026-499706
- T4https://blog.google/company-news/inside-google/message-ceo/alphabet-earnings-q3-2026/
- T4https://finance.yahoo.com/quote/GOOG/earnings/GOOG-Q3-2026-earnings_call-712854.html?fr=sycsrp_catchall
- T3https://www.cnbc.com/2026/10/28/alphabet-q3-earnings-search-ai.html
- T4https://www.seroundtable.com/google-earnings-q326-42403.html
- T4https://www.perplexity.ai/finance/GOOGL/earnings
Earlier and later calls on GOOGL
- Oct 8, 2026Lean bullish into the Q3 print.Lean bullish
Want a fresh look at GOOGL, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Oct 30, 2026. Not personalised advice. Figures use end-of-day closes.