Mostly right — but half is re-rating.
Thesis
Bull case
Bookings +35% with strengthening pricing and a third straight raise is accelerating momentum, not noise; if bookings hold >25-30% into Q4/Q1, FY27 AFFO estimates move up, the $5-6B capex program is validated as high-return AI capacity, and ~24x forward AFFO is defended by growth — with DLR read-through lifting the whole complex.
Bear case
The raise was ~2% of AFFO, one-third of it inorganic; the $4.93 EPS beat likely contains one-offs; capex intensity plus 4.1x leverage and excluded xScale spend create funding and FCF pressure; and after a relief pop, any bookings deceleration or rate backup compresses the multiple — regardless of where the exact historical baseline sits, the raise does not cover the move.
What would change our mind
- Q4 2026 annualized gross bookings growth falls below ~15% — the demand-durability leg of the re-rating fails
- Post-earnings FY27 AFFO consensus revisions come in flat or negative despite the raise, confirming the move was pure multiple expansion
- EPS reconciliation shows the Q3 beat was majority one-time items
- EQIX's premium to DLR collapses back to its historical beta without a fundamental driver
Since publication vs SPY · closed horizons are frozen
No price data after the entry date yet.
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
At ~24x forward AFFO after the pop, the price now assumes bookings momentum >25-30% persists through 2027, that the $5-6B capex program (ex-xScale) converts to double-digit organic AFFO/share growth, and that rate/REIT-multiple headwinds stay benign — a meaningful step up from the de-rated expectations priced in when the stock sat ~10% below its 52-week high pre-print.
Why the market may be wrong
Two-sided. Downside: the AFFO raise was ~2% (one-third inorganic) against a +4.8% move, so the re-rating portion unwinds if Q4 bookings growth decays toward single digits. Upside: this is the third straight >30% bookings quarter with pricing strengthening — if that run-rate holds, consensus FY27 AFFO estimates are too low and ~24x is defended by growth, making yesterday's pop look small in hindsight.
The one thing to watch
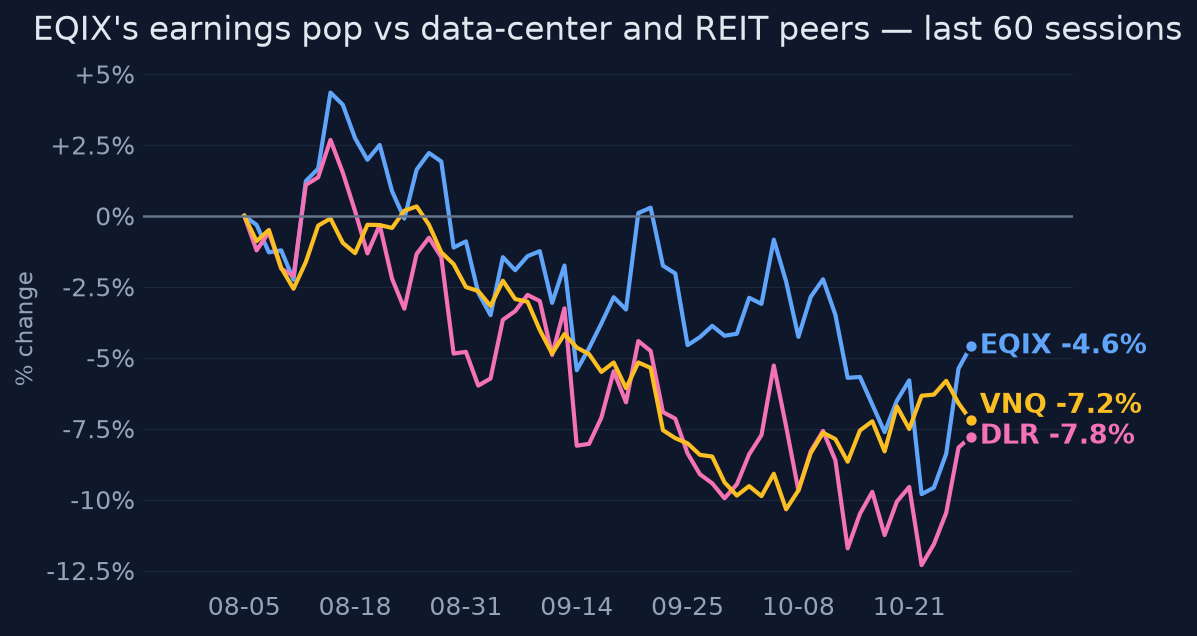
The decision variable isn't AFFO — it's the bookings-to-multiple identity: EQIX trades with 0.90 correlation to DLR, so it normally can't sustain idiosyncratic re-ratings unless its demand indicators visibly decouple from peers; the single number that licenses (or kills) the post-pop multiple is annualized gross bookings growth, and with the AFFO raise at only ~2% of value, most of the +4.8% is a bet that +35% bookings holds, not a payment for higher estimates.
Key evidence (8)
- Q3 2026 revenue $2.571B vs ~$2.56B consensus; adj. EPS $4.93 vs ~$4.12 expected (magnitude suspicious, reconciliation unverified) [T1 PR, Oct 28 2026; T4 for consensus]
- Record annualized gross bookings $533M, +35% YoY; third straight quarter >30%; MRR +11% normalized cc, churn 1.7% [T1]
- Third consecutive raise: FY26 revenue +$100M (~12% growth), EBITDA +$70M, AFFO +$90M to $4.34-4.38B; AFFO/share growth guided 11-12% [T1]
- ~$31M of the $90M AFFO raise from atNorth (equity-method, inorganic); organic AFFO/share growth 12% vs 18% headline [T1/T4]
- Capex ~$1.6B in Q3, FY guide $5-6B excluding xScale and acquisitions; net leverage 4.1x, $9.1B liquidity [T4 transcript; T1 IR]
- Current valuation ~24x 2026 AFFO ($104B mkt cap / $4.36B AFFO) [computed from T1]; comparison to an estimated ~19-21x on 2025 guidance rests on illustrative assumed share prices ($750-800) in a search result that itself disclaims reliability — not a verified historical multiple [T1-derived estimate, unverified]
- 60-day correlation to DLR 0.90 — EQIX normally trades as a DLR proxy, making the idiosyncratic pop unusual [computed from price history]
- Stock was -7% over 6m and ~9.7% below 52w high into the print; +4.8% partly a relief move off a de-rated base [market data]
Catalysts and risks
Catalysts
- Q4 2026 earnings ~Feb 9, 2027 — next bookings print and initial FY27 guidance
- Post-earnings sell-side estimate revisions over the coming weeks
- DLR's Q3 report — peer confirmation or divergence of the demand signal
- xScale capex/economics disclosures and any atNorth return detail
- Rate path — REIT multiples remain rate-sensitive
Risks
- Bookings growth decays toward single digits, orphaning the multiple-expansion portion of the move
- The $4.93 vs $4.12 EPS beat proves non-operating and reverses on reconciliation scrutiny
- Capex/xScale funding needs pressure FCF and push leverage above the 'moderate increase' promise
- Rates back up, compressing data-center REIT multiples sector-wide
- Re-correlation to DLR (0.90) drags EQIX back if the peer prints weak
What to watch
- Annualized gross bookings ($533M, +35% YoY) — the one number; watch Q4 print
- Ex-atNorth organic AFFO/share growth (~12%) vs the 18% headline
- FY27 consensus AFFO revisions in the next 2-4 weeks
- xScale capex excluded from the $5-6B guide — total capital envelope
- EQIX/DLR relative performance — whether the decoupling persists or mean-reverts
Market snapshot when the call was made 2026-10-28
Price
| Return 1w | +1.3% |
| Return 1m | -0.8% |
| Return 3m | -3.8% |
| Return 6m | -7.0% |
| Return 1y | +21.5% |
| From 52-week high | -9.7% |
| Realized vol, 20d | 28% |
| SPY 3m / 1y | +4.1% / +12.7% |
| QQQ 3m / 1y | +6.2% / +15.5% |
Technicals
EQIX technicals as of 2026-10-28: last close $1,007.66; 20d SMA 1,002.42 (bearish); 50d SMA 1,024.46; 12d EMA 990.61; 26d EMA 1,002.84; RSI 14 49.1 (balanced); 20d vol 27.9%; volume x1.3 vs 20d avg
Next earnings: 2027-02-09 AMC
Verifier notes REVISE · opinion revised once
Unsupported claims
- 'the stock now trades at ~24x 2026 AFFO, above the ~19-21x range it carried on 2025 numbers' — the 19-21x comparison is not an observed historical multiple. The search_web evidence derives 19-21x only from an explicitly 'assumed' illustrative share price of $750-$800 applied to 2025 AFFO guidance, and states the historical/10-year average multiple is 'not determinable from the retrieved authoritative sources.' Presenting it as the multiple the stock 'carried' overstates the evidence; the re-rating claim (and thus the 'half the pop is multiple expansion' framing) rests partly on this unverified baseline.
Weakly sourced
- The ~19-21x 2025 valuation baseline relies on illustrative arithmetic in a search result that itself disclaims reliability; it is the sole support for the 'full valuation / re-rating' conclusion and should be labeled as estimated, not stated as fact.
Corrections applied
- Hedge the 2025 multiple baseline: e.g., 'roughly 24x forward AFFO, versus an estimated ~19-21x on 2025 guidance at typical 2025 share prices (baseline not verified against a historical multiple series)'. Alternatively, reframe the multiple-expansion argument purely on the ~2% AFFO raise vs the +4.8% move, which is directly supported by T1 evidence.
Sources (19 · T1 = primary filings)
- T1https://www.prnewswire.com/news-releases/equinix-reports-third-quarter-results-and-raises-2026-guidance-302922…
- T4https://finance.yahoo.com/markets/stocks/articles/equinix-eqix-q3-2026-earnings-054402183.html
- T4https://247wallst.com/cards/equinix-q3-2026-earnings-eqix-01m622mkgehpch3gsdnxdr279b
- T1https://investor.equinix.com/
- T4https://au.investing.com/news/stock-market-news/equinix-q3-2026-slides-record-bookings-drive-raised-outlook-93…
- T4https://www.investing.com/news/transcripts/earnings-call-transcript-equinix-tops-q3-2026-profit-estimates-shar…
- T4https://in.investing.com/news/stock-market-news/equinix-q3-2026-slides-record-bookings-drive-raised-outlook-93…
- T4https://ng.investing.com/news/stock-market-news/equinix-tops-q3-estimates-raises-guidance-on-strong-demand-93C…
- T4https://finance.yahoo.com/markets/stocks/articles/equinix-inc-eqix-q3-2026-051050078.html
- T4https://ca.investing.com/news/stock-market-news/earnings-call-transcript-equinix-tops-q3-2026-profit-estimates…
- T4https://www.tradingkey.com/news/transcripts/262249675-tradingkey
- T4https://www.marketbeat.com/instant-alerts/transcript-what-equinix-eqix-said-on-its-q3-earnings-call-2026-10-28…
- T4https://www.benzinga.com/news/26/10/62680564/equinix-q3-2026-earnings-call-transcript
- T1https://investor.equinix.com/financial-information
- T1https://investor.equinix.com/sec-filings/proxy-filings/content/0001101239-25-000028/0001101239-25-000028.pdf
- T4https://newsroom.equinix.com/2026-07-29-Equinix-Reports-Second-Quarter-Results,-Raises-2026-Guidance-and-Long-…
- T1https://www.sec.gov/Archives/edgar/data/1101239/000110123925000028/june302025pressrelease-8k.htm
- T1https://investor.equinix.com/sec-filings/all-sec-filings/content/0001101239-25-000035/0001101239-25-000035.pdf
- T1https://investor.equinix.com/sec-filings/all-sec-filings/content/0001101239-25-000035/eqix-063025xpressrelease…
Want a fresh look at EQIX, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Oct 29, 2026. Not personalised advice. Figures use end-of-day closes.