Oversold de-rating, not deterioration.
Thesis
Bull case
At ~15x forward earnings, you pay a mature-multiple for a platform still compounding bookings at 18-22% with operating income growing 30% and margins expanding. Q3 (Nov 4) confirms guidance, FCF conversion holds, and buybacks at the 52-week low accelerate per-share value. The AV transition plays out as fragmentation — multiple suppliers (Waymo, Tesla, Nuro, Zoox, Baidu, Pony) all needing demand aggregation, payments, insurance, and dispatch liquidity that only Uber has at scale — making Uber the toll road on autonomy rather than its casualty. Sell-side targets of $101-106 (UBS, BofA) get re-anchored as AV fear fades; even a partial re-rating to 20x on $4.45 2027E EPS implies ~$89.
Bear case
The Waymo pattern is the bear case in miniature: partner with Uber to access demand, build rider relationships and brand, then go direct — Phoenix already ended, Austin/Atlanta reportedly next before 2028 expiry. Every AV partner Uber onboards is a potential future disintermediator, and Uber has no proprietary AV stack as a fallback. If autonomous rides carry structurally lower take rates (fleet owners capture the economics Uber's drivers today absorb), then even 'winning' the aggregation layer means compressing revenue per trip in its highest-margin segment. Add insurance cost pressure, Q3 EPS guidance already below consensus, FCF quality questions (SBC, insurance reserves, working-capital dependence), and a multiple that can stay compressed for years because the terminal-value debate cannot be settled by any single quarter.
What would change our mind
- Q3 gross bookings growth below ~15% constant-currency or a Q4 guide below mid-teens — would convert this from multiple compression into genuine deceleration
- Disclosure that AV rides on Uber's platform carry a materially lower take rate than driver-based trips
- Waymo launching direct ride-hailing in Austin/Atlanta with disclosed trip share gains at Uber's expense
- FCF conversion deteriorating materially versus adjusted EBITDA (insurance reserve build, working-capital reversal) for two consecutive quarters
- FY27 consensus EPS cut below ~$4.00 while the stock holds ~15x — meaning the de-rating was justified by fundamentals, not fear
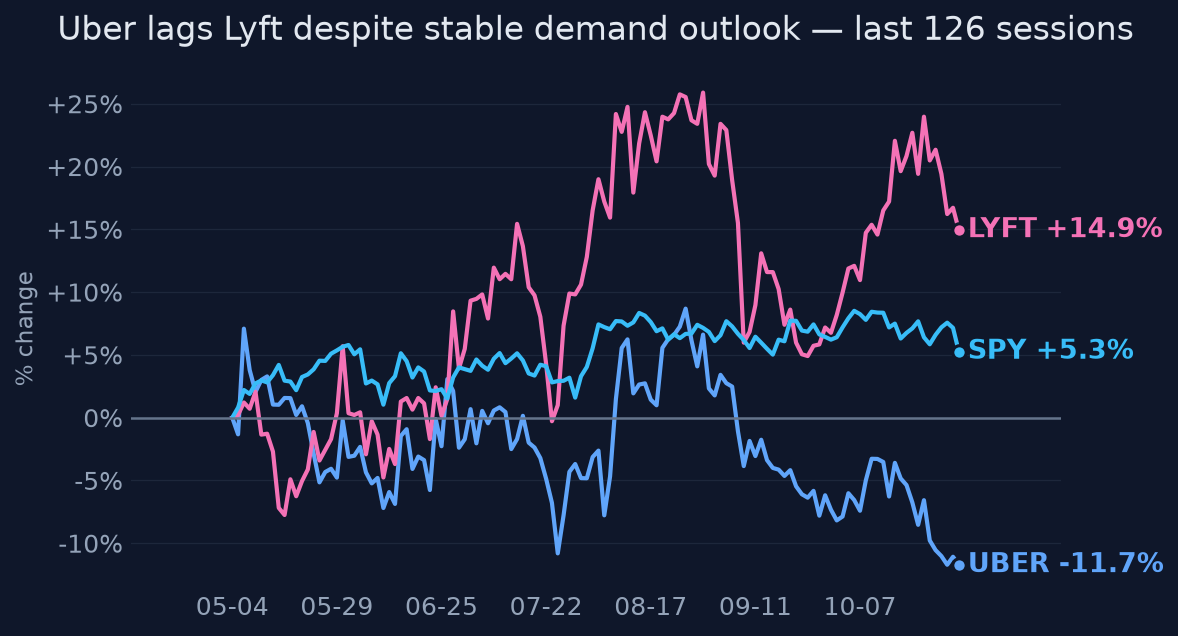
Since publication vs SPY · closed horizons are frozen
No price data after the entry date yet.
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
At ~15-16x forward EPS versus a 24-28x recent range, the market appears to price a material probability that AV operators (Waymo now, Tesla later) capture the customer relationship and compress Uber's take rate and mobility economics over a multi-year horizon. The price also embeds modest near-term caution: Q3 adjusted EPS guide of $0.84-0.88 came in below ~$0.89 consensus, and near-term revenue estimates drifted ~0.6% lower over three months. Notably, the market is NOT pricing an imminent demand collapse — bookings expectations remain ~18-22% growth.
Why the market may be wrong
Three cracks in the bear narrative: (1) There is no public evidence yet that Waymo is taking aggregate share from Uber — Waymo is gaining share of autonomous rides, a small slice of the total market, while Uber's trips grew 18%. (2) LYFT is +12% over six months, outperforming UBER by ~25pp — if the market truly believed AVs kill rideshare economics, the weaker, subscale player would not be outperforming; this looks like an Uber-specific premium-multiple reset and skepticism about the aggregator strategy, not a sector death sentence. (3) Uber's asset-light, multi-partner AV strategy (Nvidia targeting 28 cities by 2028, plus Nuro, Lucid, Zoox, Wayve, Baidu, Pony) could make Uber the demand layer for a fragmented AV supply base rather than a victim of it.
The one thing to watch
The de-rating is a terminal-value repricing, so earnings beats alone will not re-rate the stock — the variable that actually moves the thesis is evidence on AV ride economics through Uber's platform (take rate on autonomous trips versus driver-based trips) and whether partners monetize through or around Uber. Watch that disclosure, not the headline bookings beat; the LYFT divergence (+25pp over 6m) tells you the market is specifically doubting Uber's aggregation-layer claim, not rideshare demand.
Key evidence (10)
- Q2'26 (reported Aug 5, 2026): gross bookings $58.02B (+22% YoY, beat ~$57.06B consensus); revenue $14.19B (+12%, slight miss); operating income $1.9B (+30% YoY) [T1 SEC filing, T2 Reuters]
- Q3'26 guidance: gross bookings $58.25-60.25B (18-22% cc growth); adjusted EPS $0.84-0.88, below ~$0.89 consensus [T2 Reuters, T1 SEC]
- FY2025 SEC figures: revenue $52.0B (+18%), operating income $5.6B (10.7% margin, up from 6.4% in FY24); FY25 EPS $4.73 [T1 SEC XBRL]
- Consensus: 2026E revenue ~$57.9B, EPS ~$3.18-3.36; 2027E revenue ~$66.8B, EPS ~$4.42-4.53; revisions roughly flat over 3 months [T4 consensus aggregators — treat as directional]
- Forward P/E ~15-16x (Nov 1-2, 2026) vs 24.2x end-2025 and 28.2x end-2024 [T4 StockAnalysis/ChartMill — methodology varies by provider]
- Price action: -31.9% over 1y, at 52-week low, 34.6% below 52w high, RSI 27.8, 20d vol at 11th percentile; 97% idiosyncratic vs SPY over 60d [computed from price history]
- Waymo: ~250k paid rides/week across ~15 cities; Phoenix Uber-Waymo partnership ended 2026; Austin/Atlanta deals expire 2028 with Waymo reportedly planning direct ride-hailing there before expiry [T2/T3 mixed with T4 — Phoenix termination and ride-volume figures need primary confirmation]
- Tesla robotaxi: constrained Austin launch June 2026, a handful of cities, no disclosed ride volumes; Cybercab deployment early [T2/T4]
- Uber AV strategy: AV operations in 7 cities targeting 15 by YE26; Nvidia partnership targeting 28 cities by 2028 (Reuters, Mar 2026); partners include Nuro, Lucid, Zoox, Wayve, Baidu, Pony [T2 Reuters for Nvidia; rest mixed tier]
- LYFT +12.1% over 6m vs UBER -13.1%; DASH -32.7% over 1y vs UBER -31.9% [computed from price history]
Catalysts and risks
Catalysts
- Q3 2026 earnings Nov 4, 2026 — bookings vs $58.25-60.25B guide, adjusted EBITDA vs $2.86-2.96B guide, FCF and buyback disclosure
- Management commentary on Waymo relationship post-Phoenix and AV partnership economics (take rate on autonomous trips)
- Waymo city launches and any move to direct ride-hailing in Austin/Atlanta before 2028 deal expiry
- Tesla robotaxi expansion cadence and any disclosed ride volumes
- Uber AV partnership launches toward the 15-city YE26 target; Nvidia/Uber deployment progress
- Driver-classification or insurance-regulation developments
Risks
- AV disintermediation: partners use Uber's distribution then build direct channels (Phoenix precedent)
- Structurally lower take rate on AV rides compresses mobility revenue per trip even if volumes hold
- Terminal-value bear case is unfalsifiable on a 3-6 month horizon — multiple compression can persist indefinitely
- Q3 EPS guide already below consensus; another soft profit guide could extend the selloff despite bookings strength
- Insurance costs and FCF quality (SBC, reserves, working capital) could undermine the cash-conversion story
- Key AV facts (Waymo 250k rides/week, Phoenix termination details, ~$102 consensus PT) rest partly on T4 sources and may be imprecise
What to watch
- Nov 4 print: bookings vs guide, EBITDA vs $2.86-2.96B guide, and especially any disclosure of AV trip economics or take rate on autonomous rides
- Buyback pace and average repurchase price at depressed levels
- Waymo weekly ride volume trajectory and direct-channel moves in Uber-partnered cities
- Tesla robotaxi geographic expansion and first disclosed volume metrics
- LYFT vs UBER relative performance — continued LYFT outperformance supports the Uber-specific-multiple-reset framing; convergence would suggest sector-wide AV repricing
- FY26/27 consensus revision direction after Q3 — stable estimates with a falling price strengthens the compression thesis; cuts weaken it
Market snapshot when the call was made 2026-10-30
Price
| Return 1w | -2.2% |
| Return 1m | -3.9% |
| Return 3m | -8.9% |
| Return 6m | -13.1% |
| Return 1y | -31.9% |
| From 52-week high | -34.6% |
| Realized vol, 20d | 27.7% |
| SPY 3m / 1y | -0.3% / +9.9% |
| QQQ 3m / 1y | -1.4% / +8.6% |
Technicals
UBER technicals as of 2026-10-30: last close $65.25; 20d SMA 68.65 (bearish); 50d SMA 71.21; 12d EMA 67.11; 26d EMA 68.57; RSI 14 27.8 (oversold); 20d vol 26.4%; volume x1.1 vs 20d avg
Sources (23 · T1 = primary filings)
- T2https://www.reuters.com/business/autos-transportation/uber-nvidia-plan-robotaxi-rollout-28-cities-starting-nex…
- T4https://www.empower.com/the-currency/life/robotaxi-us-expansion-news
- T4https://robonomics.substack.com/p/fact-check-on-self-driving-3q26
- T4https://www.theverge.com/transportation/1023143/rivian-autonomy-point-to-point-robotaxi-q3-2026
- T4https://aiweekly.co/es/ai-use-cases/function/robotics-automation
- T4https://builtin.com/articles/robotaxi
- T4https://www.autoconnectedcar.com/2026/06/autonomous-self-driving-vehicle-news-waymo-teradar-plusai-mobileye-te…
- T4https://www.smartcitiesdive.com/news/robotaxi-wars-uber-waymo-zoox-tesla/830930/
- T1https://www.sec.gov/Archives/edgar/data/1543151/000154315126000027/uberq226earningspressrelea.htm
- T4https://finance.yahoo.com/quote/UT8.DE/earnings/UT8.DE-Q2-2026-earnings_call-661328.html
- T4https://www.perplexity.ai/finance/UBER?comparing=UBER,PGY,PLTR,TSLA,ARBE,MBLY
- T4https://www.theglobeandmail.com/investing/markets/stocks/UBER/pressreleases/1746895/uber-uber-q1-2026-earnings…
- T4https://www.bignewsnetwork.com/news/279224639/uber-building-infrastructure-to-commercialise-autonomous-mobilit…
- T4https://www.tipranks.com/news/uber-stock-forecast-what-financial-analysts-expect-ahead-of-q3-earnings
- T4https://finance.yahoo.com/markets/stocks/articles/uber-technologies-inc-uber-q2-190203049.html
- T4https://www.theglobeandmail.com/investing/markets/stocks/UBER/pressreleases/3696195/uber-q2-earnings-call-cent…
- T4https://finance.yahoo.com/markets/stocks/articles/uber-stock-expect-ubers-q3-152155585.html
- T4https://finance.yahoo.com/markets/stocks/articles/heres-expect-uber-next-earnings-222208935.html
- T4https://au.finance.yahoo.com/quote/UBER/analysis/
- T4https://www.fidelity.com/news/article/company-news/202610281523MIDNIGHTUSEQUITY_A3737508
- T4https://finance.yahoo.com/markets/stocks/articles/uber-expects-35-earnings-growth-151713916.html?fr=sycsrp_cat…
- T4https://news.alphastreet.com/uber-technologies-uber-q3-2026-preview-eps-est-0-90-reports-november-4/
- T4https://www.pricetargets.com/NYSE/Uber/
Earlier and later calls on UBER
- Oct 18, 2026Yes — derating looks overdone.Lean bullish
- Oct 6, 2026Derated, not deteriorating — lean bullish.Lean bullish
- Sep 1, 2026Yes — value is emerging here.Lean bullish
- Aug 9, 2026Not immediately; strategically, yes.Lean bullish
Want a fresh look at UBER, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Nov 2, 2026. Not personalised advice. Figures use end-of-day closes.