Mostly no — narrative premium.
Thesis
Bull case
The buyback engine is real and large: ~$826M/yr of programmatic HYPE buying against a $21.7B mcap is a structural bid few tokens have, and HIP-3 (equity perps, RWAs) is a credible option on fee-base expansion — if SPCX-type markets scale beyond growth-mode pricing and the SpaceX IPO actually confirms, today's 'rounding error' becomes a new category. HYPE has 119-138pp of 1y alpha over BTC/ETH/SOL, RSI 65 not overbought, and sits just 6.6% below ATH — momentum plus buybacks can squeeze through the unlock.
Bear case
The pop is premium on a misattributed, unverified headline; the fee contribution is provably immaterial; a 1%-of-supply core-contributor unlock lands in ~8 days; TradFi (ETFs) is distributing, not accumulating; on-chain usage (TVL, chain fees) is falling while price makes highs — a classic divergence. The $86B FDV with 76% of supply yet to unlock means every rally is sold into future emissions, and SPCX's $1.1-1.2B cross-venue OI on an unverified reference price is a liquidation-cascade candidate if the IPO rumor is denied.
What would change our mind
- Hyperliquid perp-DEX daily revenue sustains >10% above the ~$2M/day baseline for 2+ weeks with SPCX attributable — the narrative is real fee growth, not premium
- SpaceX IPO confirmed by SEC filing or T1 press — catalyst is verified and HIP-3 equity perps become a durable category
- Nov 6 unlock passes with price holding above ~$80 and ETF flows turning positive — supply absorption disproves the overhang thesis
- Assistance Fund buyback pace accelerates measurably above ~$2.3M/day
Since publication vs BTC · closed horizons are frozen
No price data after the entry date yet.
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
The price action implies the market believes SPCX-style pre-IPO equity perps are a meaningful new revenue line for Hyperliquid and that the SpaceX IPO headline is real and durable — i.e., that HIP-3 builder markets can materially expand the fee base.
Why the market may be wrong
Three errors compound: (1) venue attribution — ~54% of SPCX volume is on Binance, so Hyperliquid's actual slice is a minority of the $1.1B headline; (2) fee math — at 0.009% taker growth-mode pricing, even $300M/day of Hyperliquid SPCX volume yields only tens of thousands in daily fees versus a ~$2M/day baseline; (3) the catalyst is unverified — no SEC filing, SpaceX statement, or Reuters/Bloomberg confirmation of an IPO exists. Volume on an unverified synthetic reference price can evaporate on a denial.
The one thing to watch
Stop watching SPCX volume and watch Hyperliquid's daily perp-DEX revenue instead: because ~99% of fees fund HYPE buybacks, that single DefiLlama line is the direct pipe from any volume story to token value — and it mathematically cannot move more than ~1-2% from SPCX, which converts the 'is the rally justified' debate into a falsifiable weekly check against a ~$2M/day baseline.
Key evidence (11)
- SPCX 24h perp volume ~$1.14-1.33B across 41 markets, Binance ~$634-720M (~54%) — perpdexlist/loris.tools [T4], Oct 28-29 2026
- SPCX on Hyperliquid is a trade.xyz HIP-3 market (500k HYPE staked); launch session did only $33M volume / $21.8M OI — CoinDesk [T2], 2026-05-18
- No SEC filing or primary-source confirmation of a SpaceX IPO at $1.75T; rumor only [research sweep, Oct 29 2026]
- SPCX growth-mode fees ~0.009% taker / 0.003% maker [T4]
- Hyperliquid perps: ~$60.5M revenue last 30d, ~$834M annualized; ~99% of fees to Assistance Fund HYPE buybacks — DefiLlama [T3]
- DefiLlama 'Hyperliquid L1' chain entity shows only $11.6k/24h (gas only) — using it produces absurd 14,000x FDV/revenue; perp DEX is the correct entity
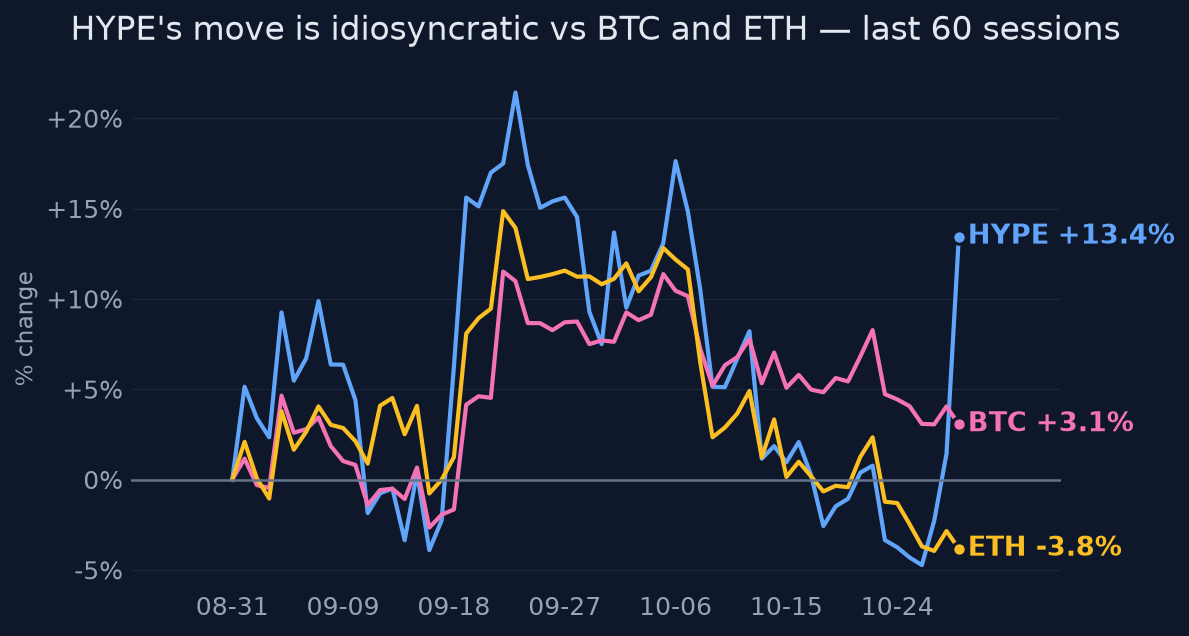
- HYPE +12.6% 1w vs BTC -4.8%, ETH -6.0%; 60d idiosyncratic share 57-70% — move is not market beta
- US spot HYPE ETFs ~-$37.1M net outflows in October, $0 on Oct 28 [T4 trackers, two corroborating]
- Nov 6, 2026 unlock ~9.9M HYPE (~$870M, 1.0% of supply) to core contributors — sources differ 8.6M vs 9.92M [T3/T4]
- L1 TVL -5.9% over 30d; chain fee trend -31.6% 30d-vs-prior; price at 100% of 20d range, 6.6% below ATH
- Mcap $21.7B vs FDV $86.4B — only ~24% of supply circulating; vesting extends into 2027-2029
Catalysts and risks
Catalysts
- Nov 6, 2026 core-contributor unlock (~9.9M HYPE) — absorption or distribution test
- Confirmation or denial of the SpaceX IPO filing (SEC/SpaceX/Reuters-Bloomberg)
- Sustained step-change (or absence thereof) in daily perp-DEX revenue over the next 1-2 weeks
- SPCX open interest unwinding — cascade risk if rumor fades
- Any HIP-3 fee-schedule change moving equity perps off growth-mode pricing
- HYPE ETF flow reversal
Risks
- Unlock overhang: 1% Nov 6, with vesting continuing into 2027-2029 against a 24% float
- Narrative unwind if SpaceX IPO is denied or quietly dropped
- Wash/incentive-driven volume on HIP-3 markets overstating product-market fit
- Regulatory risk to pre-IPO equity perps (synthetic securities on unlicensed venues)
- FDV/mcap gap means long-run sell pressure is structural, not episodic
- Key venue-attribution and flow data rests on T4 aggregators, not primary sources
What to watch
- THE number: Hyperliquid perp-DEX daily revenue on DefiLlama vs ~$2M/day baseline
- SPCX perp open interest and Hyperliquid's venue share of SPCX volume
- Nov 6 unlock recipient behavior (transfers to exchanges vs holding)
- Daily HYPE ETF net flows (BHYP/THYP/HYPG)
- Funding rates and OI on HYPE perps for crowded-long signals
- Any SEC/Reuters/Bloomberg confirmation on SpaceX
Market snapshot when the call was made 2026-10-29
Price
| Return 1w | +12.6% |
| Return 1m | +3.8% |
| Return 3m | +68.6% |
| Return 6m | +127.3% |
| Return 1y | +90.1% |
| From 52-week high | -6.6% |
| Realized vol, 20d | 66.3% |
| BTC 3m / 1y | +25.2% / -29.1% |
| ETH 3m / 1y | +21.8% / -41.6% |
| QQQ 3m / 1y | +6.2% / +15.5% |
Technicals
Sources (24 · T1 = primary filings)
- T4https://www.tradersmagazine.com/am/anthropic-pre-ipo-perpetuals-go-live/
- T4https://cipher-intelligence.io/markets/hyperliquid/spacex/
- T4https://www.theglobeandmail.com/investing/markets/stocks/INTC/pressreleases/2059310/can-you-really-buy-spacex-…
- T4https://hyperliquidguide.com/markets/xyz/spcx
- T4https://www.tokenpost.com/news/investing/39832
- T4https://cryptoticker.io/de/anthropic-ipo-hyperliquid-perps/
- T4https://talkmarkets.com/article/spacex-pre-ipo-market-goes-on-chain-hyperliquid-launches-synthetic-trading-177…
- T2https://www.coindesk.com/markets/2026/05/18/hype-pops-7-beating-bitcoin-declines-as-spacex-pre-ipo-lands-on-hy…
- T4https://www.perpdexlist.com/markets/rwa/SPCX
- T4https://loris.tools/markets/perps/spcx
- T4https://www.investing.com/equities/spcx-usd-perpetual-futures-historical-data
- T4https://pumpglass.com/smart-money/SPCXUSDT
- T3https://www.marketwatch.com/investing/stock/spcx/options
- T4https://www.coinfuty.com/coin/SPCX/overview
- T4https://www.tokenpost.com/tag/perpetual-futures
- T4https://ca.investing.com/equities/spcx-usd-perpetual-futures-scoreboard
- T3https://defillama.com/protocol/hyperliquid
- T3https://defillama.com/protocol/mass
- T3https://defillama.com/protocol/based
- T3https://defillama.com/protocol/hyperliquid-perps
- T3https://defillama.com/protocol/hyperliquid-spot-orderbook
- T3https://defillama.com/protocol/liquid-perps
- T3https://defillama.com/protocol/hyperliquid-hlp
- T3https://defillama.com/protocol/fomo
Want a fresh look at HYPE, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Oct 29, 2026. Not personalised advice. Figures use end-of-day closes.