Real fundamentals, spent catalyst.
Thesis
Bull case
Record backlog (+27% q/q) gives multi-year revenue visibility; the FY27 budget supercycle (munitions tripling, PAC-3 MSE $12.2B, THAAD $11.4B, Golden Dome) plays directly to LMT's missile and space franchises; the 2025-26 charges are behind it and F-35 framework for up to 850 jets restores Aero visibility. If Q4 margins confirm, skeptical EPS estimates chase upward and the stock re-rates through $634 toward the $670-756 target range.
Bear case
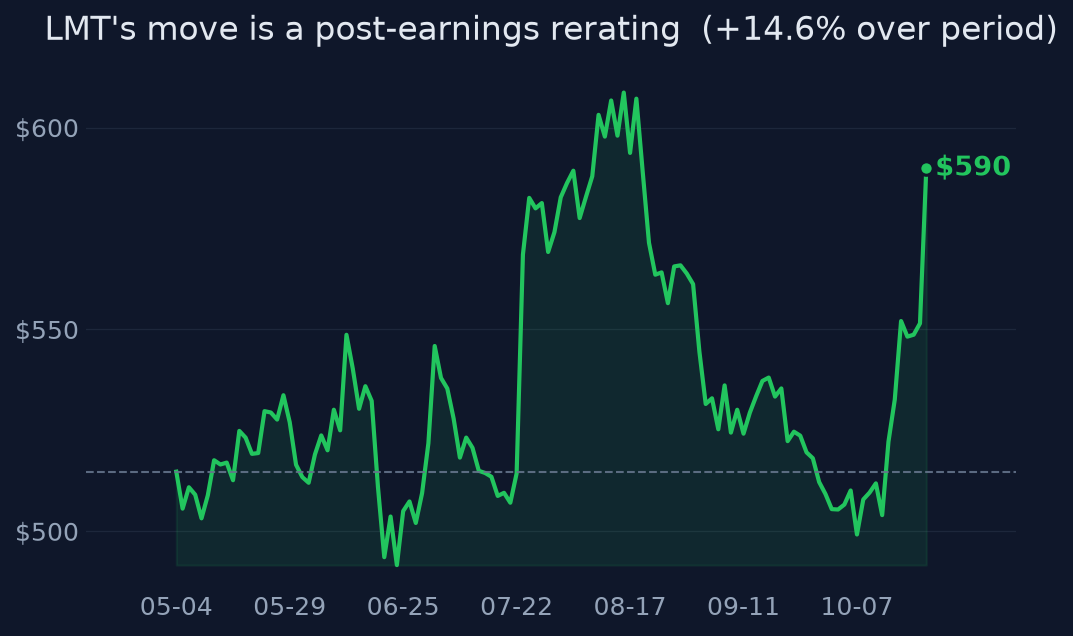
This is a gap-chase at the top of a recovery move: RSI 82, catalyst spent, 2-4% to consensus value, multiple above historical norm. Fixed-price/classified program risk is structural — one bad program erased $1.6B in 2025. Aero guidance was nudged down on F-35 timing, RMS grows only low-single-digits, EPS revisions are drifting down, and the Golden Dome/munitions upside is hostage to an unpassed reconciliation bill. Bernstein ($564), TD Cowen ($570), and Goldman ($498) all sit below the current price.
What would change our mind
- Q4 2026 segment operating margin prints materially below ~10.6% or new program charges appear — confirms the 'earnings quality is cyclical' bear case
- FY27 EPS consensus (~$32.79) gets revised down while the stock holds >20x — the re-rating thesis is dead
- Reconciliation/defense appropriation fails or Golden Dome funding is stripped — removes the FY27 growth leg
- Conversely, a pullback to ~$540-560 (50-day / Bernstein target zone) with estimates intact would invalidate the 'no edge' stance and create a buyable entry
Since publication vs SPY · closed horizons are frozen
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
At ~20x FY26 consensus EPS of $30.41 and targets clustered at $620-634, the market has priced in continued execution: margin delivery near 10.6-10.8% segment operating margin, F-35 ramp without new charges, and at least partial conversion of the FY27 budget request (including munitions tripling and Golden Dome) into booked orders. The 45% hold contingent suggests consensus itself is unconvinced there's more near-term upside.
Why the market may be wrong
Two directions. Bullish: consensus EPS estimates fell ~0.8% over 90 days even as management raised guidance — if Q4 confirms margin delivery, estimates must chase upward, and a stock at 20x with accelerating revisions re-rates. Bearish: ~$17.1B of Golden Dome funding sits in an unpassed reconciliation bill, F-35 Aero segment guidance was quietly nudged down on award timing, and the fixed-price/classified program exposure that produced $1.6B of charges in 2025 is structural, not fixed.
The one thing to watch
The tell is the estimate-revision divergence: management raised FY26 EPS guidance by $0.25 at midpoint while the sell side cut its EPS estimates ~0.8% over 90 days — the market is underwriting revenue but not margins. The variable to watch is not backlog or budget headlines; it is whether Q4 segment operating margin prints at/above ~10.6%, because that resolves who is right and determines whether 20x is a floor or a ceiling.
Key evidence (9)
- Q3 2026 (reported 2026-10-22): EPS $7.97 vs $7.52 est; revenue $20.7B (+11% y/y) vs $20.48B est [company IR, T4; corroborated Reuters]
- Record backlog $292B, +27% q/q, including $52.5B PAC-3 MSE multiyear award [company IR]
- FY26 guidance raised: sales midpoint +$250M to ~$81B, EPS to $30.35-30.75, FCF +$800M to $7.8-8.0B [company IR, 2026-10-22]
- 90-day revisions: revenue estimates +2.1%, EPS estimates -0.8% despite guidance raise [consensus aggregation, T4]
- Valuation ~20x FY26 EPS vs. above 5-yr average and sector median; 'fair, not cheap' [T4 commentary]
- Consensus targets $620-634 vs price ~$607 → 2-4% implied upside; mix 11 buy/10 hold/1 sell [MarketBeat/Barron's/MarketScreener, T4 — treat directionally]
- Prior drawdown drivers: $950M classified reach-forward loss, $1.6B total Q2'25 charges, F-35 lot timing; FY25 EPS $21.49 vs FY23 $27.55 shows earnings cyclicality [SEC XBRL + company disclosures]
- Technicals: +10.75% 1w on 2.4x volume, RSI 82.6, 12.3% below 52w high — recovery, not breakout [market data, 2026-10-22]
- FY27 budget request ~$1.5T with missile procurement ~3x to ~$95B, but ~$17.1B of Golden Dome in unpassed reconciliation [CRS/DoD, T1; CSIS, T4]
Catalysts and risks
Catalysts
- Q4 2026 earnings (January 2027) — margin print and first FY27 guidance
- FY27 appropriations / reconciliation vote — fate of ~$350B mandatory defense funding and Golden Dome
- F-35 Lot 19/20 contract award (pushed toward 2027)
- Sell-side EPS revision direction over next 90 days
- Further multiyear munitions awards converting budget into backlog
Risks
- New fixed-price/classified program charges (structural, precedent set in 2025)
- Reconciliation failure or CR delays pushing Golden Dome/new-start revenue out
- F-35 award timing slipping further; Aero guide already trimmed
- Mean reversion from RSI-82 overbought condition after catalyst exhaustion
- Multiple compression if FY27 consensus (~$32.79) gets cut on margin skepticism
What to watch
- 90-day EPS revision trend — does it turn positive after the guidance raise?
- Q4 segment operating margin vs. the ~10.6% implied full-year level
- F-35 lot award timing announcements
- Congressional action on reconciliation and FY27 defense appropriations
- Whether price holds the post-earnings gap or fills back toward $540-560
- NOC/RTX/GD earnings to separate LMT alpha from sector beta (peer multiples remain unverified)
Market snapshot when the call was made 2026-10-22
Price
| Return 1w | +10.8% |
| Return 1m | +12.4% |
| Return 3m | +1.2% |
| Return 6m | +12.1% |
| Return 1y | +22.9% |
| From 52-week high | -12.2% |
| Realized vol, 20d | 33% |
| SPY 3m / 1y | +3.4% / +13.8% |
| QQQ 3m / 1y | +3.0% / +15.2% |
Technicals
LMT technicals as of 2026-10-22: last close $589.91; 20d SMA 523.24 (bearish); 50d SMA 540.01; 12d EMA 541.22; 26d EMA 533.47; RSI 14 82.6 (overbought); 20d vol 33.3%; volume x2.4 vs 20d avg
Sources (28 · T1 = primary filings)
- T4https://investors.lockheedmartin.com/news-releases/news-release-details/lockheed-martin-reports-third-quarter-…
- T4https://investors.lockheedmartin.com/static-files/6dcc085b-63f5-49f1-8414-2dfc4b991528
- T4https://www.benzinga.com/news/26/10/62527926/lockheed-martin-q3-2026-earnings-call-transcript
- T4https://uk.finance.yahoo.com/news/lmt-q3-earnings-call-highlights-130000878.html
- T4https://www.investing.com/news/transcripts/earnings-call-transcript-lockheed-martin-tops-q3-2026-estimates-rai…
- T4https://www.investing.com/news/company-news/lockheed-martin-q3-2026-slides-strong-beat-drives-guidance-raise-9…
- T4https://au.investing.com/news/stock-market-news/lockheed-martin-q3-2026-slides-strong-beat-drives-guidance-rai…
- T4https://stockanalysis.com/stocks/lmt/transcripts/713938-q3-2026/
- T4https://investors.lockheedmartin.com/static-files/d17e20e5-ac74-4c0b-8143-74d578e0ecef
- T4https://www.kansascity.com/news/business/article317747665.html
- T4https://investors.lockheedmartin.com/news-releases/news-release-details/lockheed-martin-reports-second-quarter…
- T2https://www.reuters.com/business/aerospace-defense/lockheed-lifts-annual-forecast-missile-jet-production-ramps…
- T4https://investors.lockheedmartin.com/static-files/3b15de61-9ea7-4637-82a2-535a331218d2
- T4https://ca.investing.com/news/stock-market-news/earnings-call-transcript-lockheed-martin-tops-q3-2026-estimate…
- T4https://www.marketbeat.com/stocks/NYSE/LMT/
- T1https://www.congress.gov/crs_external_products/R/PDF/R49023/R49023.2.pdf
- T1https://www.war.gov/News/Releases/Release/Article/4466038/department-of-war-releases-the-presidents-fiscal-yea…
- T1https://www.congress.gov/crs-product/IF13264
- T1https://comptroller.war.gov/Portals/45/Documents/defbudget/FY2027/DoW_FY2027_Mandatory_Funding_Overview.pdf
- T1https://www.whitehouse.gov/wp-content/uploads/2026/04/rebuilding-our-military-fact-sheet.pdf
- T1https://www.govinfo.gov/content/pkg/BUDGET-2027-BUD/pdf/BUDGET-2027-BUD-19.pdf
- T4https://www.csis.org/analysis/tracking-fy-2027-defense-appropriations-reconciliation-and-supplemental-request
- T1https://comptroller.war.gov/Portals/45/Documents/defbudget/FY2027/fy27_Green_Book.pdf
- T4https://investors.lockheedmartin.com/node/53326/pdf
- T4https://fortune.com/company/lockheed-martin/earnings/q3-2026/
- T4https://www.marketscreener.com/news/lockheed-martin-q3-earnings-webcharts-final-ce785cded98ff42c
- T4https://news.lockheedmartin.com/news-releases?category=788&l=100
- T4https://www.marketbeat.com/instant-alerts/transcript-what-lockheed-martin-lmt-said-on-its-q3-earnings-call-202…
Want a fresh look at LMT, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Oct 23, 2026. Not personalised advice. Figures use end-of-day closes.