Real re-rating, but stale.
Thesis
Bull case
The fee switch transformed UNI into the only large-cap DEX token with live, recurring, protocol-funded burns, and burn pace was still accelerating into mid-2026. Dominant spot-DEX share, fully-vested supply, and a live v4 fee temp-check mean that if October's DeFi shock mean-reverts, fee income and the burn re-accelerate together, and the current 31% drawdown from highs looks like a liquidation-driven discount on a structural change.
Bear case
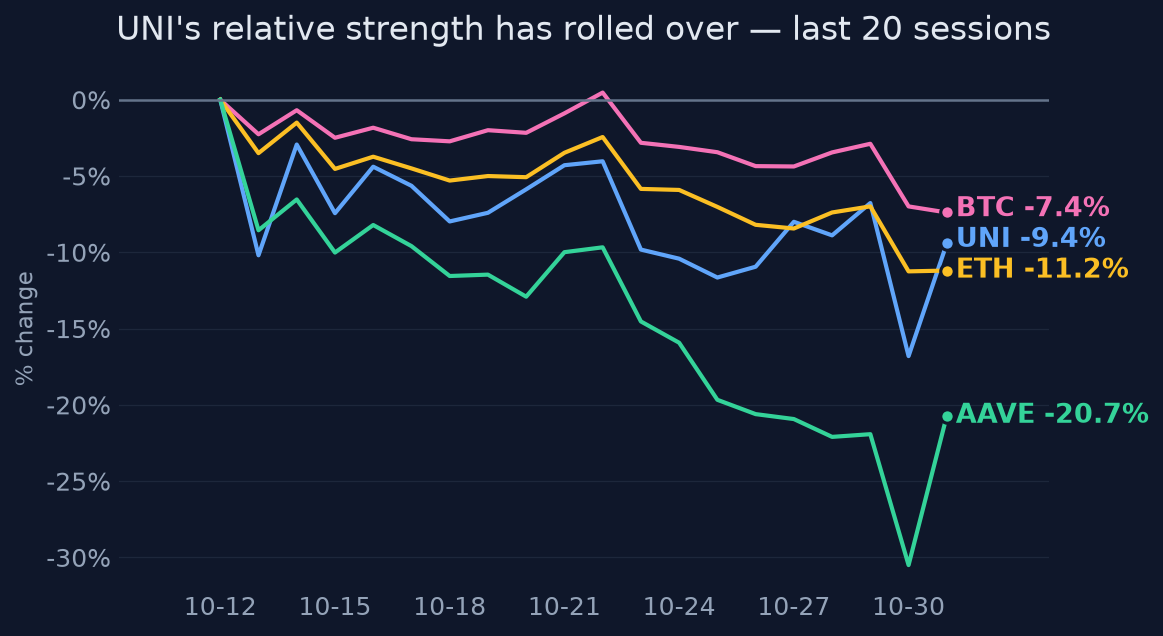
The re-rating already happened and the scan is late. Fees -55% MoM and TVL -32% 1y show usage contraction that mechanically shrinks the burn (~1.3% of supply/year even at the prior pace — too small to support 61x annualized, ~100x trailing FDV/revenue on its own). Relative strength has flipped negative against every benchmark, there are no dated catalysts in 90 days, and the token's new fee-beta means it falls hardest in exactly the liquidity downturn now underway.
What would change our mind
- Monthly burn falls and stays below ~0.5M UNI/month for 2+ consecutive months — thesis that fee accrual supports valuation is broken
- v4 protocol-fee activation is rejected or indefinitely stalled in governance
- DEX volume share loss: Uniswap weekly volume falls below PancakeSwap/Aerodrome on a sustained basis
- If fees recover >30% MoM while UNI stays >25% below its 52w high, the bearish 'stale re-rating' read is wrong and it is accumulation, not distribution
Since publication vs BTC · closed horizons are frozen
No price data after the entry date yet.
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
At ~61x FDV/annualized protocol revenue (DefiLlama annualization: FDV $6.23B vs ~$101M implied by ~$8.3M 30d revenue × 12) — and ~100x on trailing-1y revenue of ~$62M — the market prices in successful extension of protocol fees to v4 and more chains, plus fee-income recovery, such that burn accrual scales materially from the current ~1.3%-of-supply/year pace. It does not price continuation of the current fee contraction.
Why the market may be wrong
In either direction. Bulls may be wrong because burn accrual is fee-procyclical: in a DeFi downturn the buyback shrinks exactly when the token needs support, and the multiple (61x annualized, ~100x trailing) embeds expansion not yet voted in. Bears may be wrong because UNI is the only large-cap DEX token with live, rising, protocol-funded supply destruction, 70% of supply already circulating with no unlock overhang, and dominant spot-DEX share ($16.2B weekly volume vs AERO $3.4B, CAKE $5.5B) — if DEX volumes mean-revert, the burn re-accelerates and the valuation math changes quickly.
The one thing to watch
The variable that matters is not UNI's price rank but the burn's beta to fees: UNI now trades like a levered claim on DEX volume, because the fee switch made supply destruction pro-cyclical — the ~55% MoM fee drop means the burn run-rate (the entire re-rating thesis) is falling into the same October shock that hit price, so watch monthly UNI burned, not the chart.
Key evidence (9)
- Price $7.03 (2026-10-31, CoinGecko): +119.5% 6m, +61.8% 3m, but -20.8% 1m and -31% below 52w high; RSI 46, below 50d SMA
- Liquidity is real: $445M 24h volume = 10.2% of $4.39B market cap; vol 97% annualized is normal-for-UNI (69th percentile), 1m z-score -0.78 — no pump signature
- Quant: relative strength flipped vs BTC (-15% 1m after +31% 3m), ETH, QQQ and AAVE (-7% 1m); idiosyncratic share 61-68% is consistent with a token-specific driver, though it does not prove the fee switch caused the rally
- UNIfication fee switch approved Dec 2025; ~7.2M UNI burned Jan-Jul 2026, pace rising ~0.53M/mo (Jan) to ~1.77M (June) (Token Terminal [T3], Uniswap docs); asset research explicitly caveats that no event study isolates UNIfication's effect from broader market conditions
- Protocol revenue ~$28.2M Jan-Jul 2026; protocol takes ~1/6 of swap fee on enabled v2/v3 pools across 11 chains; v4 fee activation temp-check live on governance forum [T1]
- Usage deteriorating: TVL $3.62B, -31.8% 1y, -9.5% 30d; 30d fees $90.9M, -55% vs prior 30d (DefiLlama [T3])
- Valuation: DefiLlama's FDV-to-annualized-revenue ratio of 61.3x implies ~$101M annualized revenue (consistent with 30d revenue $8.35M × 12); against trailing-1y revenue of ~$62M the multiple is ~100x; mcap/TVL 1.21 (DefiLlama)
- October 2026 drawdown was market-wide: ~$485M BTC ETF outflows Oct 7, ~$1.18B ETH ETF outflows for the month, long-liquidation cascade Oct 12-16, stablecoin supply ~$12.7B below May peak — UNI's 1m drop is largely sector beta
- No upcoming unlocks (vesting ended 2024-2025, ~70% circulating), no UNI spot ETF, no dated catalysts within 90 days besides the v4 fee temp-check
Catalysts and risks
Catalysts
- Governance vote on activating v4 protocol fees (temp-check live on gov.uniswap.org) — would expand the fee base feeding the burn
- Extension of protocol fees to additional chains/v4 pools
- Monthly burn disclosures — re-acceleration above ~1.8M UNI/mo would re-ignite the thesis
- DeFi TVL / DEX volume recovery after October deleveraging (weekly DEX volume already rebounded to $49.4B on Oct 30, Uniswap leading at $16.2B)
- Possible execution/verification of the approved 100M UNI treasury burn
Risks
- Burn pro-cyclicality: further fee contraction cuts the accrual engine precisely during drawdowns
- Valuation risk: 61x annualized (~100x trailing) FDV/revenue prices fee-switch expansion not yet enacted; v4 vote failure or delay removes the next leg
- Attribution risk: the fee-switch narrative is the leading explanation for the 2026 rally but is not causally proven — if the re-rating was mostly market beta, the 'structural change' discount case weakens
- Sector beta: UNI beta ~1.8 to BTC; another leg of ETF-outflow/liquidation-driven market weakness drags it regardless of fundamentals
- Data ambiguity: conflicting circulating-supply figures (624M vs ~893M) and unverified 100M treasury-burn execution make accrual-per-token math approximate
- Competitive fragmentation across Solana/Base/BNB DEX venues eroding Uniswap's fee pool
What to watch
- Monthly UNI burn run-rate and TokenJar/Firepit balances (the single most decision-relevant live metric)
- Uniswap governance forum: v4 protocol-fee temp-check progression to an on-chain vote
- DefiLlama 30d fees and TVL trend — stabilization after the -55% print
- Weekly DEX volume share (Uniswap vs AERO/CAKE/JUP)
- BTC/ETH ETF flows and stablecoin supply as the beta driver of any UNI move
- UNI/BTC relative-strength ratio — already flipped negative; a reclaim of the 50d would signal the re-rating leg resuming
Market snapshot when the call was made 2026-10-31
Price
| Return 1w | +1.1% |
| Return 1m | -20.8% |
| Return 3m | +61.8% |
| Return 6m | +119.5% |
| Return 1y | +20.4% |
| From 52-week high | -31.2% |
| Realized vol, 20d | 96.7% |
| BTC 3m / 1y | +23.4% / -28.5% |
| ETH 3m / 1y | +21.0% / -40.8% |
| QQQ 3m / 1y | -1.4% / +8.6% |
Technicals
Verifier notes REVISE · opinion revised once
Weakly sourced
- The claim that the December 2025 'UNIfication' fee switch 'drove' the 2026 rally is stated as fact in the direct_answer, but the asset research explicitly caveats that sources do not establish causation and do not permit separating UNIfication's effect from broader market conditions — the opinion should present it as the supported-but-not-proven leading explanation (which the thesis partially does via idiosyncratic-variance evidence).
Internal inconsistencies
- Valuation arithmetic is internally inconsistent: the opinion claims 'FDV $6.23B vs ~$62M annualized protocol revenue ≈ 61x' in both market_expectation and key_evidence. 6.23B / 62M = ~100x, not 61x. The 61.3x figure in the evidence is DefiLlama's fdv_to_annualized_revenue ratio, which implies annualized revenue of ~$101M (consistent with 30d revenue $8.35M × 12). The $62M figure is trailing-1y revenue, which is not what the 61x ratio uses. The opinion mixes the two, so either the multiple or the revenue figure is wrong as stated.
Corrections applied
- Fix the valuation line to use consistent figures: either 'FDV $6.23B vs ~$101M annualized protocol revenue (DefiLlama annualization of ~$8.3M 30d revenue) ≈ 61x' or 'FDV $6.23B vs ~$62M trailing-1y revenue ≈ 100x'. Note that on trailing revenue the multiple is even higher, which if anything strengthens the valuation-risk point.
- Soften 'the 2026 rally was driven by' the fee switch to 'is best explained by' or 'coincided with', consistent with the evidence caveat that no event study isolates UNIfication's effect from market beta.
Sources (24 · T1 = primary filings)
- T4https://developers.uniswap.org/docs/protocols/protocol-fee/overview
- T4https://developers.uniswap.org/docs/get-started/concepts/fees
- T4https://developers.uniswap.org/docs/protocols/protocol-fee/concepts/fees
- T4https://developers.uniswap.org/docs/protocols/protocol-fee/guides/best-practices
- T4https://developers.uniswap.org/docs/ecosystem/governance/uni
- T4https://developers.uniswap.org/docs/ecosystem/governance/faqs
- T3https://tokenterminal.com/resources/newsletter/uniswap-after-unification
- T1https://gov.uniswap.org/t/temp-check-activate-v4-protocol-fees/26162
- T3https://defillama.com/chain/robinhood-chain?
- T3https://defillama.com/chain/ethereum?tvl=false&events=false&chainRevenue=true
- T3https://defillama.com/?tvl=false&stablecoinsMcap=true
- T4https://cryptodaily.co.uk/2026/10/defi-tvl-falls-below-90b-as-morpho-gains-while-lido-and-aave-lose-liquidity
- T4https://www.tokenpost.com/news/investing/44615
- T4https://thecryptobasic.com/2026/10/27/cardano-stablecoin-supply-tops-defi-tvl-by-11-million/
- T4https://x.com/RWAFoundation_/status/2112153452625145918
- T4https://econotimes.com/Decentralized-Exchange-Trading-Falls-6-94-to-44-18-Billion-1761234
- T4https://cryptoslate.com/bitcoin-beats-the-sp-500-on-most-trading-days-but-still-loses-the-month/
- T4https://finance.yahoo.com/markets/crypto/articles/bitcoin-etfs-bleed-636-million-155041101.html
- T4https://finance.yahoo.com/markets/crypto/articles/bitcoin-etfs-snap-two-week-140103174.html
- T4https://martyau79.substack.com/p/26oct2026-crypto-and-macro-liquidity
- T4https://www.mytokencap.com/news/601102/
- T4https://alphapoint.com/blog/flows-out-rails-in-etfs-bleed-while-banks-and-exchanges-build-onchain
- T3https://research.glassnode.com/the-week-onchain-week-42-2026/
- T4https://finance.yahoo.com/markets/crypto/articles/bitcoin-enters-october-4-problems-151855980.html
Earlier and later calls on UNI
- Oct 20, 2026Real activity — but stalling.Lean bearishview changed
Want a fresh look at UNI, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Oct 31, 2026. Not personalised advice. Figures use end-of-day closes.