Right direction, wrong magnitude.
Thesis
Bull case
The quarter showed Altria's pricing model still works: it outperformed the industry volume decline, expanded margin, grew on! double digits, raised guidance, and expanded the buyback. If FDA enforcement crushes illicit competitors and NJOY re-enters in 2027, a structurally higher multiple is defensible — Goldman's $83 path via duty drawback and the PM manufacturing deal is concrete, and even at $78 the stock yields ~5.7% with buyback support.
Bear case
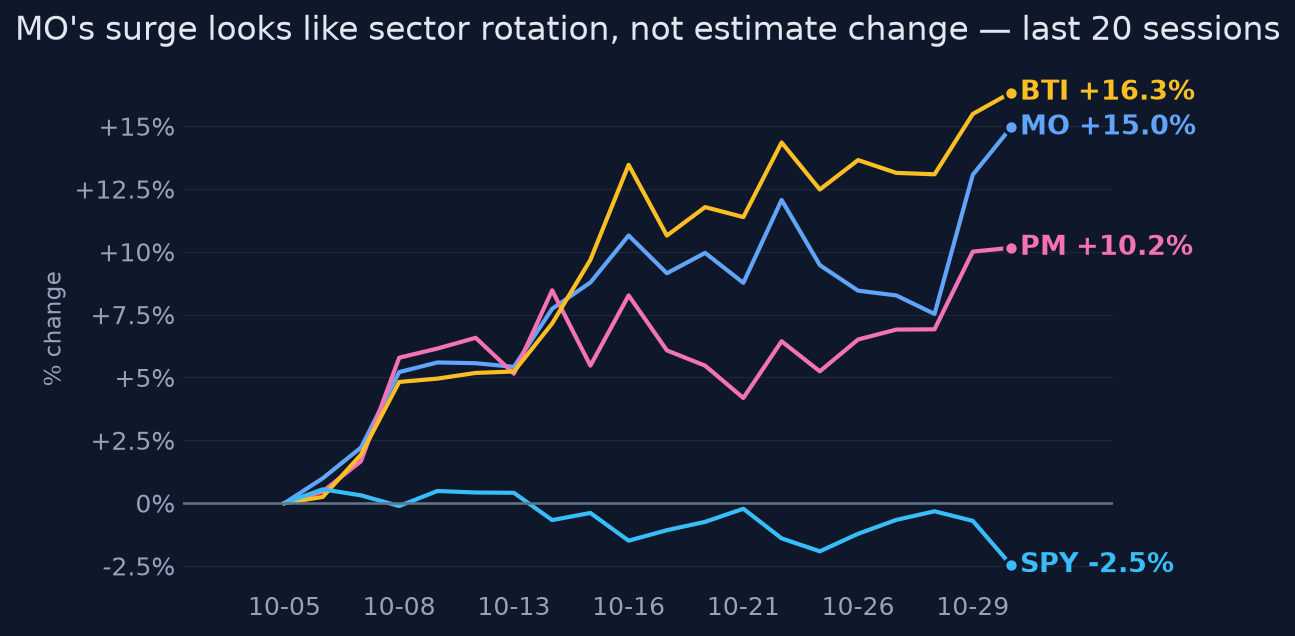
Nothing about the earnings stream changed — estimates are flat — yet the stock costs 17% more. You're paying ~13.8x for ~4-5% EPS growth built on perpetually outrunning a ~4% volume decline with price increases, an ~89% GAAP payout, and a yield that has compressed as the price rose. If the defensive rotation unwinds (60d beta to SPY is -0.85), MO falls while the market rises.
What would change our mind
- FY27 consensus EPS revisions turn meaningfully positive (>3%), converting the re-rating into estimate-led upside
- FDA issues concrete enforcement/rulemaking that visibly lifts on! or NJOY volumes
- The expanded buyback is sized large enough to add >1% to EPS annually
- Stock holds above ~$75 through an equity-market rebound, proving the re-rating is not rotation-dependent
- A sourced historical forward-P/E series shows ~13.8x is within, not above, Altria's normal range — which would remove the core overvaluation leg
Since publication vs SPY · closed horizons are frozen
No price data after the entry date yet.
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
At ~13.8x forward earnings and a 52-week high, the price assumes the re-rating sticks: that defensive/yield demand persists, that FDA enforcement against illicit e-vapor and pouches improves the competitive backdrop, and that on! plus a 2027 NJOY re-entry convert option value into a credible growth story justifying a sustained premium multiple.
Why the market may be wrong
Re-ratings without estimate revisions are fragile. The consensus mean target ($73.70, T3/T4 aggregators) already sits below the price, Barclays cut to $60, and only Goldman ($83) underwrites the new level — on duty-drawback and a PM manufacturing deal that don't start until early 2027. If the equity market stabilizes and the defensive bid fades, there is no earnings upgrade to catch the stock; if ~13.8x proves to be well above Altria's historical range (unverified in this research), the downside from compression is material.
The one thing to watch
Watch the dividend yield, not the earnings: as the price ran from ~$71.50 to $78, the yield compressed from ~6.2% to ~5.7%, so the income case — the main reason to own a ~4%-declining-volume business — is weaker at exactly the price where the stock most needs incremental buyers. (The research did not establish a historical yield floor, so treat this as a valuation-arithmetic observation, not a proven support mechanism.)
Key evidence (8)
- Q3 2026 (Oct 29): adj EPS $1.52 vs $1.51 est, +4.8% YoY; revenue net of excise $5.44B +3.6%; FY26 guidance raised to $5.66-5.74 [Altria IR, T1]
- Cigarette shipments -2.9% reported (~-4% trade-adjusted) vs ~-5% industry; smokeable op income +3.9% at 64.5% margin [Altria IR, T1]
- on! volume +13.3% to 47.8M cans, +110bps retail share [T4 Yahoo reprints of Q3 content, consistent with the T1 release but not independently sourced to it]
- Consensus 2026 EPS $5.67 (vs $5.68 three months ago), 2027 $5.88 unchanged [MarketWatch T3 / T4]
- +16.6% 1-month return, 2.6-sigma vs own history; PM +11.0%, BTI +15.7%, SPY -1.1% same month; MO 60d beta to SPY -0.85 [quant analysis]
- Consensus Hold, mean target $73.70, Barclays $60, Goldman $83 Buy [T3/T4 aggregators — the 'price above consensus target' argument rests on these]
- Dividend $4.44/yr = ~5.7% yield at $78 vs ~6.2% at $71.50; payout ~77-78% of adjusted EPS [Altria IR T1 / T4]
- No verified historical forward-P/E or yield time series was available in the research; any 'vs history' valuation comparison is general market knowledge pending verification [planner digest]
Catalysts and risks
Catalysts
- Q4 2026 earnings (~late Jan/early Feb 2027) and FY27 guidance
- Dollar size/execution pace of the expanded buyback (unspecified in excerpts)
- FDA premarket-review framework reconsideration and enforcement actions against illicit e-vapor/pouches
- NJOY ACE market re-entry timing
- Philip Morris manufacturing agreement start (early 2027) and duty-drawback benefits
- Broad equity market stabilization reversing the defensive rotation
Risks
- Multiple compression with flat estimates: on 2026E EPS of $5.67, 10x = $56.70 (-27%) and 11x = $62.37 (-20%), i.e. ~20-27% downside if the stock re-rates to that range
- Cigarette volume decline re-accelerating beyond pricing power
- Rotation reversal: MO's negative beta means it underperforms in any equity recovery
- Yield compression reducing the stock's appeal to income buyers at current prices
- Buyback expansion size disappoints
What to watch
- Forward P/E vs Altria's own historical range — the research could not source a historical series; verifying whether ~9-11x is the right comparison is the single most important open item
- Dividend yield — whether ~5.5-5.7% attracts buyers or marks a new regime
- 2027 EPS revision trend ($5.88 currently)
- on! shipment growth and share each quarter
- FDA enforcement announcements and NJOY re-entry date
- SPY correlation — does MO hold gains if equities recover
Market snapshot when the call was made 2026-10-30
Price
| Return 1w | +5.0% |
| Return 1m | +16.6% |
| Return 3m | +14.3% |
| From 52-week high | +0.0% |
| Realized vol, 20d | 27.4% |
| SPY 3m / 1y | -0.3% / +9.9% |
| QQQ 3m / 1y | -1.4% / +8.6% |
Technicals
MO technicals as of 2026-10-30: last close $78.03; 20d SMA 73.10 (bullish); 50d SMA 70.46; 12d EMA 74.50; 26d EMA 72.82; RSI 14 69.4 (balanced); 20d vol 27.7%; volume x2.4 vs 20d avg
Verifier notes REVISE · opinion revised once
Unsupported claims
- "Altria's historical ~9-11x range" (answer, thesis, what_to_watch) is stated as fact, but the evidence bundle explicitly says no verified historical forward-P/E series exists and that this comparison 'rests on general market knowledge, not a sourced time series, and should be checked.' This is the anchor of the 'one number to check' framing, so presenting it as established fact overstates the evidence.
- "The dividend yield... has compressed through the level that historically floors the stock" and "every prior MO pullback was arrested by yield buyers" (most_differentiated_insight) and "the thinnest income cushion in years" (answer): the evidence documents only two yield points (~5.7% at $78 vs ~6.2% at $71.50). No historical yield-floor level, no pullback-arrest history, and no multi-year yield series appear anywhere in the bundle. These claims are the opinion's most differentiated insight and rest on nothing in the evidence.
- "highest multiple in years" (why_this_matters): same evidentiary gap as the 9-11x claim — the bundle contains no historical multiple series to establish 'highest in years.'
Weakly sourced
- on! volume +13.3% to 47.8M cans and +110bps retail share are cited only to T4 Yahoo reprints of Q3 content — acceptable as corroboration of the T1 release but tagged T4 in the key_evidence while being load-bearing for the 'fundamentals improved' leg of the thesis.
- Consensus Hold / mean target $73.70 / Barclays $60 rest on T3 (MarketWatch) and T4 (MarketScreener-via-FactSet) aggregators; the opinion appropriately tags them but the entire 'price above consensus target' argument depends on these.
Internal inconsistencies
- No band violation: LEAN_BEARISH with conviction 5 is inside the 5-6 band, and direct_answer ('right direction, wrong magnitude') is consistent with a mild bearish lean.
- Derived arithmetic error in risks: 'Multiple compression back toward 10-11x with flat estimates = 15-25% downside.' On 2026E EPS ($5.67), 10x = $56.70 (-27%) and 11x = $62.37 (-20%), i.e., ~20-27% downside. The stated 15-25% only approximately holds if 2027E EPS ($5.88) is used (17-25%), which is not the multiple basis used elsewhere in the opinion (~13.8x is computed on 2026E).
Corrections applied
- Hedge the historical-multiple claim wherever it appears: e.g., 'versus Altria's historical ~9-11x range (general market knowledge — no sourced time series was available; verify before relying on it),' matching the caveat already present in what_to_watch, or drop the specific range and say only that ~13.8x is elevated relative to the stock's recent history pending verification.
- Rewrite most_differentiated_insight to what the evidence supports: the yield has compressed from ~6.2% to ~5.7% as the price rose, weakening the income case at current levels — remove 'compressed through the level that historically floors the stock,' 'every prior MO pullback was arrested by yield buyers,' and 'thinnest income cushion in years' unless a historical yield series is sourced.
- Fix the downside arithmetic: state either '~20-27% downside to 10-11x 2026E EPS' or specify the 2027 EPS basis if retaining ~15-25%.
Sources (15 · T1 = primary filings)
- T1https://investor.altria.com/press-releases/news-details/2026/Altria-Reports-2026-Third-Quarter-and-Nine-Months…
- T4https://finance.yahoo.com/quote/ALTR.VI/earnings/ALTR.VI-Q3-2026-earnings_call-660056.html
- T4https://finance.yahoo.com/markets/stocks/articles/altria-group-inc-mo-q3-211357305.html
- T4https://finance.yahoo.com/markets/stocks/articles/altria-group-inc-q3-2026-215421683.html
- T4https://www.2firsts.com/news/altria-showcases-ploom-marlboro-heated-tobacco-sticks-and-non-nicotine-energy-pro…
- T4https://tobaccoinsider.com/tobacco-industry-highlights-october-24-october-30-2026/
- T4https://finance.yahoo.com/markets/stocks/articles/altria-group-mo-said-q3-121430229.html
- T4https://au.finance.yahoo.com/news/mo-q3-earnings-call-highlights-130000373.html
- T4https://finance.yahoo.com/markets/stocks/articles/altria-pays-89-3-earnings-164500505.html
- T4https://247wallst.com/investing/2026/10/31/realty-income-and-4-more-high-yield-dividend-stocks-for-november/
- T1https://investor.altria.com/press-releases/news-details/2026/Altria-Reports-2026-First-Quarter-Results-Reaffir…
- T4https://finance.yahoo.com/markets/stocks/articles/altria-spending-more-capex-other-233002723.html
- T4https://ca.finance.yahoo.com/news/altria-group-6-2-dividend-133318872.html
- T4https://www.marketbeat.com/instant-alerts/filing-altria-group-inc-mo-stock-ashton-thomas-securities-llc-trims-…
- T4https://247wallst.com/investing/2026/10/23/altria-pays-out-89-3-of-its-earnings-as-dividends-heres-why-that-nu…
Want a fresh look at MO, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Nov 2, 2026. Not personalised advice. Figures use end-of-day closes.