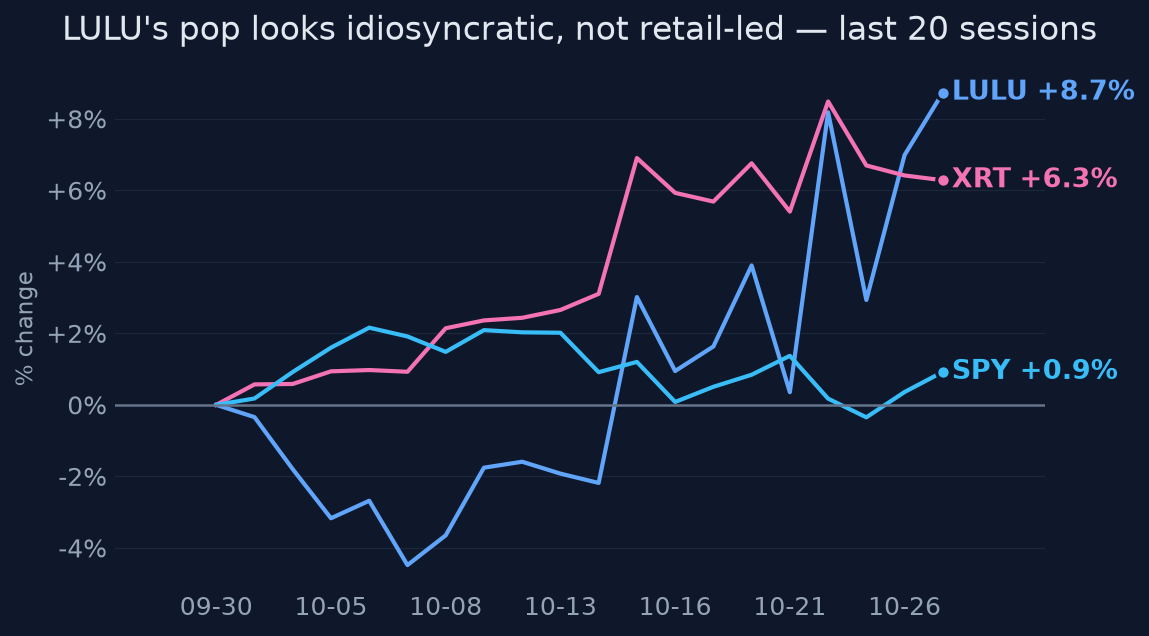
Mostly no — it's noise.
Thesis
Bull case
At ~12x forward earnings with a credible ex-Nike leadership team, stabilization in Americas comps toward flat could drive meaningful multiple expansion toward historical norms; further tariff refunds (excluded from FY guidance) are a free option, and markdown pressure is guided to moderate by Q4. Whether a squeeze dynamic would amplify this is unknown — the evidence contains no short-interest data.
Bear case
The E in P/E is collapsing: Q3 guided EPS down ~63% YoY, underlying Q2 op margin ex-refund was ~13% vs 20.7%, and the new product team cannot affect results until FY27. Consensus sitting above the guide top means either more downward revisions or an earnings miss — with the stock already above the mean target, downside toward Wolfe's $75 is plausible if comps worsen beyond the reported -8%.
What would change our mind
- Americas comparable sales improve meaningfully from the reported -8% toward flat at the Q3 print — validates the bounce and undermines the bearish lean
- Consensus Q3 EPS converges to/below guidance AND the company still beats, showing estimate risk has cleared
- Confirmed additional tariff refunds or a raised FY outlook would add un-modeled earnings support
Since publication vs SPY · closed horizons are frozen
No price data after the entry date yet.
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
The market appears to be pricing a plausible-but-unproven product/brand reset under the new leadership team, treating ~12x forward earnings as a floor in a stock already 51% below its 52-week high. Consensus still sits above management guidance, implying the sell-side either expects a beat or hasn't finished revising down.
Why the market may be wrong
Both directions possible: bulls may be early because the new CPO arrived after Q3 was effectively over, so the next print reflects the old regime; bears may be wrong because valuation (12x fwd vs 28.9x 5y median trailing) and depressed positioning already embed a lot of bad news, and stabilization in Americas comps could trigger a sharp re-rating. The key falsifiable gap: consensus $1.05 Q3 EPS vs guided max $0.98 — that gap must close before or at the print.
The one thing to watch
The bounce day coincided almost exactly with the new CPO/COO start date (Oct 26), so the market is trading personnel, not demand — which means the variable to watch is not the stock's reaction but whether consensus Q3 EPS (currently $1.05, above the $0.98 guide top) converges down before the print; if it doesn't, the earnings event is a trap door regardless of the leadership story.
Key evidence (7)
- Oct 27 move: +1.63% to $104.59 on 0.9x 20-day average volume; no SEC filing, earnings, or IR release that day [T1/T2 searches, market data]
- Oct 7 announcement [T1 SEC 8-K exhibit; T2 Reuters]: Maggie Gauger (ex-Nike) President & Chief Product Officer and Joseph Godsey COO, both effective Oct 26; CEO Heidi O'Neill started Sept 2026
- Q2 FY26 (reported Sept 3, 2026): revenue $2.42B miss, EPS $2.92 beat but included $134.5M (~$0.86/sh, ~560bps op margin) IEEPA tariff refund [T4 summaries of T1 press release]; Americas comps reported at -8% via Reuters as relayed by T4 aggregators — not yet confirmed against the primary release, which matters because this anchors the thesis
- Second FY26 guidance cut: revenue $10.35-10.5B (-5-7%), EPS $9.48-9.73; Q3 guide revenue -10-11% YoY, EPS $0.93-0.98 vs $2.59 PY, op margin ~6.5% vs 17% [T1 press release via search]
- Estimate momentum: 0 upward / 14 downward EPS revisions for the October quarter in 30 days to Oct 20; consensus $1.05 EPS vs guide top $0.98 [T4 aggregators]
- Valuation/positioning: fwd P/E ~12.0-12.6x vs 5y median trailing 28.9x; Wolfe Underperform $75 PT (Oct 22); consensus Hold with six Sells, mean target ~$96 — below current price [T4]
- Technical context: 1m return z-score 0.71 (unremarkable for a 46%-vol stock); still -51.5% below 52w high, +13.8% above 52w low; no short-interest data was available in the evidence, so any short-covering framing is speculative
Catalysts and risks
Catalysts
- Fiscal Q3 FY26 earnings (expected early December 2026; date unconfirmed)
- Q3 EPS vs $0.98 guide top and $1.05 consensus — the convergence gap resolves
- Holiday quarter commentary: markdown trajectory (guided +60bps Q3, flat Q4) and inventory
- Any announcement of additional tariff refunds (excluded from current FY guide)
- Potential further estimate revisions as sell-side digests leadership transition
Risks
- Americas comps worse than the reported -8% at Q3 print confirms the reset isn't working (figure itself needs primary-source confirmation)
- Consensus fails to converge to guidance, making the print a mechanical miss
- Departures of Chief Brand Officer and Chief Supply Chain Officer (Nov 6) create execution gaps mid-transition
- Value-trap dynamic: optically cheap multiple on collapsing earnings
- High idiosyncratic vol (46%) means narrative reversals are fast and large in both directions
What to watch
- Americas comparable sales at Q3 print (the single decision number; reported -8% in Q2 — confirm the baseline against the Q2 press release)
- Consensus Q3 EPS revisions between now and the print — does $1.05 converge toward $0.98?
- Confirmed Q3 earnings date from IR
- Markdown rate vs the guided +60bps in Q3
- Official confirmation of Tara Poseley board appointment [currently T4 only]
Market snapshot when the call was made 2026-10-27
Price
| Return 1w | +4.7% |
| Return 1m | +4.0% |
| Return 3m | -12.1% |
| Return 6m | -26.6% |
| Return 1y | -41.3% |
| From 52-week high | -51.5% |
| Realized vol, 20d | 45.7% |
| SPY 3m / 1y | +5.5% / +13.6% |
| QQQ 3m / 1y | +9.0% / +16.9% |
Technicals
LULU technicals as of 2026-10-27: last close $104.59; 20d SMA 96.82 (bearish); 50d SMA 103.68; 12d EMA 99.70; 26d EMA 99.69; RSI 14 68.3 (balanced); 20d vol 46.1%; volume x0.9 vs 20d avg
Verifier notes REVISE · opinion revised once
Unsupported claims
- The opinion repeatedly describes LULU as 'heavily shorted' (thesis, market_expectation, bull_case's 'violent re-rating in a heavily shorted stock'), but the evidence bundle contains no short-interest data whatsoever — no short % of float, days-to-cover, or borrow data appears in any tool result. The short-covering/squeeze framing in the bull case rests on this unverified premise.
Weakly sourced
- Americas comps of -8% (the opinion's designated 'one number to check') is sourced only to T4-tagged search summaries citing Reuters reporting; the T1 press release excerpt in the bundle does not itself show the -8% figure. The opinion's own key_evidence tag ('T4 summaries of T1 press release') is honest about this, but given this number anchors the entire recommendation, it warrants an explicit caveat that it is not confirmed against the primary release.
Corrections applied
- Either remove the 'heavily shorted' characterization or soften it to reflect what the evidence shows (e.g., 'deeply de-rated stock with 95% idiosyncratic share and elevated skepticism — six Sell ratings, Wolfe Underperform'), and reframe the bull-case re-rating mechanism as multiple expansion on comp stabilization rather than a short squeeze, unless short-interest data is actually retrieved.
- Add a caveat to the 'one number' framing that the -8% Americas comps figure comes from Reuters reporting as relayed by T4 aggregators and should be confirmed against the Q2 press release; alternatively cite the T1 press release directly if it contains the figure.
Sources (16 · T1 = primary filings)
- T4https://english.aawsat.com/fashion/5314602-lululemon-forecast-cut-hits-shares-underscores-challenge-next-ceo
- T4https://www.perplexity.ai/finance/LULU?comparing=LULU,DECK,8016.T,8022.T,3591.T,COLM
- T4https://ca.finance.yahoo.com/quote/LULU/news/
- T4https://stockanalysis.com/stocks/lulu/
- T4http://perplexity.ai/finance/LULU?comparing=LULU,1361.HK,UAA,ONON,ADS.DE,PUM.DE
- T4https://finance.yahoo.com/quote/LULU/news/
- T4https://www.marketbeat.com/instant-alerts/filing-lululemon-athletica-inc-lulu-stock-sold-by-robeco-institution…
- T4https://www.marketbeat.com/stocks/NASDAQ/LULU/news/
- T2https://www.reuters.com/business/retail-consumer/lululemon-puts-nike-veteran-charge-product-ceo-oneill-looks-r…
- T1https://www.sec.gov/Archives/edgar/data/1397187/000139718726000131/lulu-20260930xex991.htm
- T4https://money.usnews.com/investing/news/articles/2026-10-07/lululemon-puts-nike-veteran-in-charge-of-product-a…
- T4https://corporate.lululemon.com/about-us/leadership-team
- T4https://www.theglobeandmail.com/business/article-lululemon-leadership-shakeup-new-executive-roles-heidi-oneill…
- T4https://corporate.lululemon.com/newsroom
- T2https://www.reuters.com/sustainability/boards-policy-regulation/recent-leadership-changes-global-consumer-good…
- T4https://www.retailgazette.co.uk/blog/2026/10/tara-poseley-lululemon/
Earlier and later calls on LULU
- Oct 7, 2026Cheap, but prove it in December.No clear edgeview changed
- Sep 7, 2026Yes — both, hard. Differently priced.Neutralview changed
Want a fresh look at LULU, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Oct 28, 2026. Not personalised advice. Figures use end-of-day closes.