Yes — both, hard. Differently priced.
Thesis
Bull case
LULU: new CEO inherits a deliberately depressed baseline; at ~10x cut EPS, any stabilization in comps (even -5% vs -10%) or confirmation the Sept guide is the floor triggers a violent re-rating toward the mid-teens multiple — 30-50% upside on flat fundamentals. NKE: revenue decline is only 1-4% and running/North America are inflecting; if the Oct 1 report shows inventory cleanup complete and China stabilizing, FY27 estimates stop falling and a 22x multiple on a recovering ~$2.25 FY28 EPS (per the June 2026 estimate note) implies roughly $49-50 — meaningful upside from $38 if the inflection is confirmed.
Bear case
LULU: comps of -10% with Alo/Vuori taking structural share is not a guidance problem, it's a franchise problem — the new CEO may cut again, tariffs/de minimis costs keep compressing the 56.6% gross margin, and 10x 'cheap' becomes 10x of a lower number. NKE: JPMorgan's below-consensus $1.55 FY27 EPS may still be high, China weakness persists into FY28, and 22x trough earnings means the stock can fall another 25-30% just by de-rating to a normal consumer multiple while estimates fall.
What would change our mind
- LULU bullish-reset thesis is invalidated if Q3 (Dec 9) comps are worse than -10% or FY26 guidance is cut again — that confirms structural decline, not a kitchen-sink reset
- LULU thesis is also invalidated if gross margin falls below ~55%, indicating the tariff/mix pressure is overwhelming the model
- NKE caution is invalidated (turning constructive) if the Oct 1 report shows flat-to-positive currency-neutral revenue and FY27 guidance implies H2 growth — that would justify the premium multiple
- The 'dip is over' framing for either stock is invalidated if FY27 consensus EPS keeps falling after the next reports while prices hold — that would be multiple expansion on deteriorating fundamentals, not a bottom
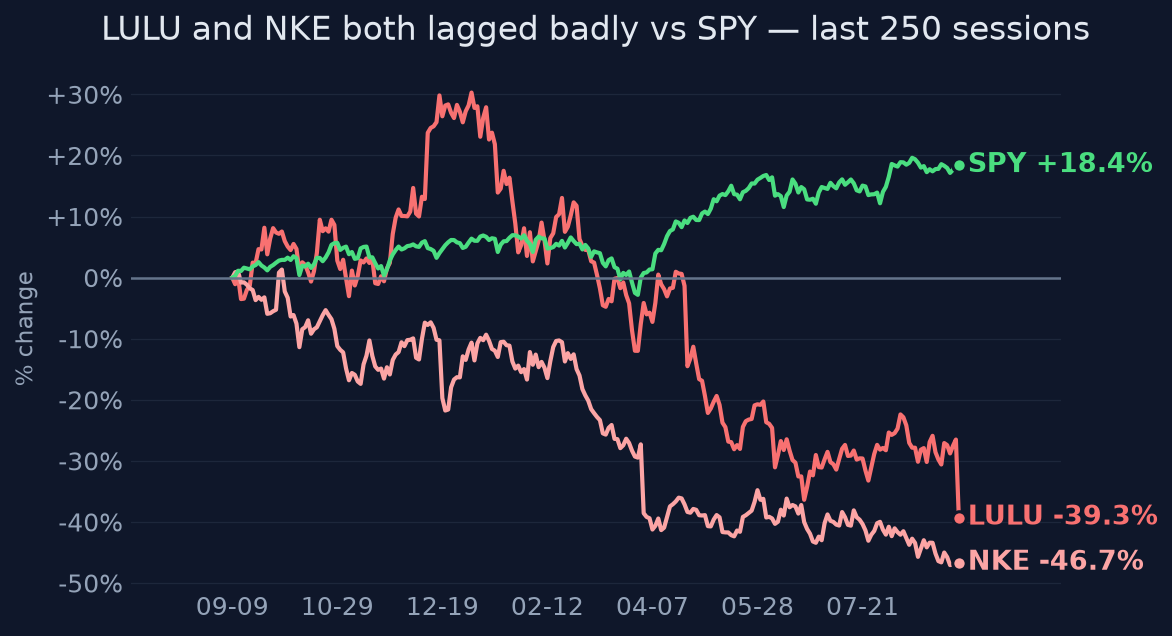
Since publication vs SPY · closed horizons are frozen
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
LULU at ~10x cut FY26 EPS is priced for the decline to continue or worsen — the market assumes the Sept 3 guide is not the final cut and that Alo/Vuori share gains are structural. NKE at ~22x trough EPS is priced for a successful Elliott Hill turnaround inflecting in FY27 H2 — the market is paying a premium multiple for a recovery that has not yet appeared in the numbers.
Why the market may be wrong
For LULU: if new CEO Heidi O'Neill deliberately reset guidance to a beatable floor (the 'baseline so low it might actually help' framing), the market is pricing a further deterioration that may not come, and 10x a $9.50+ EPS base with a still-56%+ gross margin business leaves room for sharp multiple recovery. For NKE: the market may be wrong in the opposite direction — paying 22x+ for FY27 EPS of ~$1.55-1.71 while some broker commentary sees stabilization not arriving until FY28 means the 'dip' could still be expensive.
The one thing to watch
The two dips look identical on a chart but are priced as opposite bets: LULU's ~50% crash has taken it to ~10x already-cut earnings (priced for things to get worse), while NKE's ~50% crash still leaves it at ~22x trough earnings (priced for a turnaround that hasn't shown up) — so the variable to watch isn't the price decline, it's whether LULU's Dec 9 comps stabilize versus whether NKE's Oct 1 report confirms FY27 is still a down year.
Key evidence (10)
- LULU: $100.61, -51.2% 1y, at exact 52-week low, -16.7% in the final week on 6.2x average volume and ~78% realized vol (capitulation-type trading) [market data, 2026-09-04]
- LULU cut FY26 guidance twice: June 4 to $11.0-11.15B rev / $10.95-11.15 EPS, then Sept 3 to $10.35-10.50B rev (-5% to -7% y/y) / $9.48-9.73 EPS [Reuters T2, company release, 2026-09-03]
- LULU Q2 FY26 (ended Aug 2, 2026): revenue ~$2.4B down ~4% y/y, comps -10%, EPS $2.92 beat; drivers cited: weak US traffic, product missteps, tariffs, end of de minimis [company release / CNBC T3]
- LULU CEO transition: Heidi O'Neill incoming, announced around the Sept 3, 2026 report [Reuters T2]
- LULU trades at ~10.4x the cut FY26 EPS midpoint vs EPS of $14.64 in FY2024 [SEC XBRL fundamentals]
- NKE: $38.40, -47.9% 1y, within 0.7% of 52-week low, orderly decline (32% vol, below-average volume) [market data, 2026-09-04]
- NKE FY2026: revenue $46.4B (vs $51.4B FY24), EPS $2.10 (vs $3.73); Q4 reported EPS $0.72 flattered by a $986M IEEPA tariff-refund benefit ($0.52/sh) — underlying adj. EPS $0.20 [Reuters T2, 2026-06-30]
- NKE guided to continued revenue declines through H1 FY27; management: turnaround 'not there yet', China weak [Reuters T2, 2026-07-01]
- NKE estimate cuts ongoing: Evercore FY27 EPS to $1.65 (June), JPMorgan downgraded to Underweight with FY27 EPS $1.55 vs consensus ~$1.71 (Aug 4, 2026); separate broker commentary sees real stabilization only in FY28 [Investing.com T4, corroborated by Reuters coverage]
- NKE forward P/E ~22-22.5x on still-falling estimates; June 2026 note cut FY28 EPS to $2.25 from $2.45 [YCharts/market snapshots T4 — no primary-source historical multiple series verified]
Catalysts and risks
Catalysts
- NKE Q1 FY27 earnings October 1, 2026 — test of whether revenue decline is bottoming; guided low-to-mid-single-digit decline
- LULU Q3 FY27 earnings December 9, 2026 (consensus EPS ~$2.44, revenue ~$2.58B) — first full read on whether Sept 3 guidance was the floor and early O'Neill strategy
- Heidi O'Neill's first strategic moves / investor communications as LULU CEO (Q4 2026)
- Tariff and de minimis policy developments affecting both companies' cost guidance
- Any China demand data points ahead of NKE's report
Risks
- LULU guidance is cut a third time, confirming structural share loss to Alo/Vuori rather than a cyclical traffic dip
- NKE's Oct 1 report shows China deteriorating and pushes the turnaround timeline into FY28, forcing another estimate-cut cycle on a 22x multiple
- Tariff/de minimis costs exceed what both companies have guided
- LULU's elevated volatility (~78% 20d realized) means position-sizing risk is high even if the thesis is right
- Key valuation claims (forward P/E levels, historical multiple ranges) rest on T4 sources, not verified primary data
What to watch
- NKE Oct 1, 2026 report: currency-neutral revenue vs the guided low-to-mid-single-digit decline, China growth rate, and whether FY27 EPS consensus (~$1.71) stops falling
- LULU Dec 9, 2026 report: comparable sales vs Q2's -10%, any guidance change, and O'Neill's commentary on product/merchandising fixes
- LULU weekly volume/volatility normalization — capitulation volume (6.2x avg) resolving into accumulation would support a bottom
- Estimate revision direction for both: the dips only become buys when revisions flatten
- Alo/Vuori momentum indicators (store openings, funding, any share data) as the structural threat variable for LULU
Market snapshot when the call was made 2026-09-04
Price
| Return 1w | -16.7% |
| Return 1m | -19.3% |
| Return 3m | -11.9% |
| Return 6m | -40.9% |
| Return 1y | -51.2% |
| From 52-week high | -53.4% |
| Realized vol, 20d | 77.8% |
| SPY 3m / 1y | +4.4% / +18.6% |
| QQQ 3m / 1y | +2.0% / +25.0% |
Technicals
LULU technicals as of 2026-09-04: last close $100.61; 20d SMA 118.92 (neutral); 50d SMA 118.40; 12d EMA 116.70; 26d EMA 118.20; RSI 14 36.5 (balanced); 20d vol 72.8%; volume x6.2 vs 20d avg
Next earnings: 2026-12-09 AMC
Verifier notes REVISE · opinion revised once
Unsupported claims
- Bull case for NKE: 'a 22x multiple on a recovering $2.50 FY28 EPS path justifies upside from $38' — the $2.50 FY28 EPS figure appears nowhere in the evidence. The only FY2028 EPS figures in the bundle are from the June 2026 note: FY28 EPS cut to $2.25 from $2.45. $2.50 exceeds even the pre-cut number, overstating the quantified upside in the bull scenario (22x $2.25 = ~$49.50, not ~$55).
Weakly sourced
- 'JPMorgan says stabilization may not arrive until FY28' — the evidence supports that 'some broker commentary' saw real stabilization only in FY2028, and separately that JPMorgan downgraded NKE to Underweight with below-consensus FY27 EPS of $1.55 (T4 source), but the bundle never explicitly attributes the FY28-stabilization view to JPMorgan. The attribution should be softened to 'some brokers/commentary' or re-cited. Note: the opinion does appropriately self-flag the T4 basis of its valuation claims in key_evidence and risks, which mitigates the multiple-related sourcing issues.
Corrections applied
- Replace '$2.50 FY28 EPS path' with the evidence-supported figure: 'a recovering ~$2.25 FY28 EPS (per the June 2026 estimate note)' — implying ~$49-50 at 22x rather than ~$55, or reframe as an unquantified scenario.
- Change 'JPMorgan says stabilization may not arrive until FY28' to 'some broker commentary sees stabilization not arriving until FY28' (JPMorgan is only evidenced for the Underweight downgrade and the $1.55 below-consensus FY27 EPS).
Sources (16 · T1 = primary filings)
- T2https://www.reuters.com/business/retail-consumer/lululemon-cuts-annual-revenue-profit-forecast-2026-09-03/
- T4https://corporate.lululemon.com/newsroom/press-releases/2026/09-03-2026-210528733
- T4https://www.marketbeat.com/instant-alerts/guidance-lululemon-athletica-nasdaq-lulu-updates-fy-2026-earnings-gu…
- T3https://www.cnbc.com/2026/09/03/lululemon-lulu-q2-2026-earnings.html
- T4https://www.investing.com/equities/lululemon-athletica-earnings
- T4https://www.marketbeat.com/earnings/reports/2026-9-3-lululemon-athletica-inc-stock/
- T4https://www.marketbeat.com/instant-alerts/guidance-lululemon-athletica-nasdaq-lulu-releases-q3-2026-earnings-g…
- T2https://www.reuters.com/markets/companies/LULU.O/
- T2https://www.reuters.com/legal/transactional/nike-edges-past-quarterly-revenue-estimates-2026-06-30/
- T2https://www.reuters.com/business/retail-consumer/nike-stumbles-china-woes-cautious-outlook-temper-turnaround-h…
- T2https://www.reuters.com/business/retail-consumer/nike-third-quarter-sales-beat-estimates-2026-03-31/
- T3https://www.cnbc.com/2026/04/01/nike-q3-2026-turnaround-drags-china-sales-slump.html
- T4https://investors.nike.com/investors/news-events-and-reports/investor-news/investor-news-details/2026/NIKE-Inc…
- T4https://www.benzinga.com/markets/earnings/26/07/60207942/nike-ceo-elliott-hill-delivers-q4-reality-check-nothi…
- T4https://finance.yahoo.com/quote/NKE/earnings/NKE-Q4-2026-earnings_call-629525.html
- T4https://investors.nike.com/investors/news-events-and-reports/investor-news/investor-news-details/2026/NIKE-Inc…
Earlier and later calls on LULU
- Oct 28, 2026Mostly no — it's noise.Lean bearishview changed
- Oct 7, 2026Cheap, but prove it in December.No clear edgeview changed
Want a fresh look at LULU, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Sep 7, 2026. Not personalised advice. Figures use end-of-day closes.